Cash Flow Statement: How It Works, Key Sections And Examples
The cash flow statement is a vital financial compass for any business. A cash flow statement is your financial compass, crucial in revealing the reality beneath the surface.
A cash flow statement provides a detailed breakdown of a company’s cash inflows and outflows over a specific period. This financial document categorizes cash movements into operating, investing, and financing activities, helping stakeholders understand the organization’s liquidity position.
Whether it’s money made from sales, spent on new machinery, or used to pay debts, the cash flow statement lays it all out, offering a clear view of a company’s financial health.
Key Takeaways
- Financial Clarity: A cash flow statement details incoming and outgoing cash, highlighting financial strength and operational efficiency.
- Investment Insights: It helps investors assess liquidity and predict future cash flows, which is crucial for making investment decisions.
- Risk Management: By tracking cash flow, businesses can identify financial risks early and adjust strategies accordingly.
- Budgeting Accuracy: Regular cash flow analysis supports precise budgeting and prevents financial shortfalls.
- Operational Planning: Ensures companies have sufficient cash to fund daily operations, promoting sustainable business practices.
What Is A Cash Flow Statement (CFS)?
A cash flow statement (CFS) tracks cash movement in and out of a business over a specific period. It details how the company’s operations are generating cash. It also analyzes how the money is invested and how financing activities impact liquidity.
This statement is key to assessing a company’s ability to pay its bills, fund its operations, and invest in growth. It breaks down cash flow into three main categories:
- Operating Activities: This includes cash from sales and cash for operating expenses, taxes, and interest. It shows how much cash is generated from the company’s core business operations.
- Investing Activities: This section reports cash spent on long-term assets, like property and equipment, or money received from their sale. It reflects the company’s investment in its future growth.
- Financing Activities: This area covers cash from issuing stocks or bonds, dividend outflows, and repayments of borrowed funds. It shows how the company funds its operations and growth through borrowing or equity financing.
The cash flow statement is a vital tool for managers, investors, and creditors. It helps them gauge an organization’s financial health, especially its liquidity and solvency.
How Cash Flow Statements Work

A cash flow statement is a crucial financial document. It records a business’s cash inflows and outflows over a specific period in order. This statement is key for assessing a company’s liquidity, flexibility, and performance. Here’s how cash flow statements work –
Balance Sheet
The balance sheet presents a consolidated snapshot of a company’s financial standing at a given point in time. It lists the company’s assets, liabilities, and equity and shows what it owns and owes.
The basic accounting equation is assets = liabilities + shareholders’ equity. This balance is crucial for financial integrity and helps stakeholders assess the company’s financial health and stability.
Income Statement
The income statement, or profit and loss statement, shows the company’s performance over a period. It reflects how revenue turns into net income. It records all revenues and expenses, including sales, cost of goods sold, and operational expenses. This statement is key to understanding the company’s profits and efficiency. It shows strengths and areas for improvement.
Cash Flow Statement
The cash flow statement details cash transactions from operations, investments, and financing. It shows the true liquidity of the business. It distinguishes between the cash generated and used during the period. This clarity is crucial for managing day-to-day operations, fulfilling investment strategies, and handling financial obligations.
Statement Of Shareholders’ Equity
The statement of shareholders’ equity tracks changes in equity throughout a financial period. This document shows all changes in profits, losses, dividends, and stock transactions. It provides a transparent view of how the company’s actions and policies affect shareholder value. It is a critical tool for investors and analysts to assess the company’s financial health and policy impacts over time.
Accrual Accounting
Accrual accounting is a method where transactions are recorded when they occur, regardless of when cash transactions happen. This approach gives a better view of a company’s finances. It includes receivables and payables, which show all financial obligations and resources.
Cash Accounting
Cash accounting involves recording transactions only when cash is exchanged. This method is simpler and is typically employed by small businesses that do not need to account for receivables or payables. It clarifies cash flow. But, it may show a company’s full financial status differently than accrual accounting.
What Are The Key Sections Of A Cash Flow Statement?
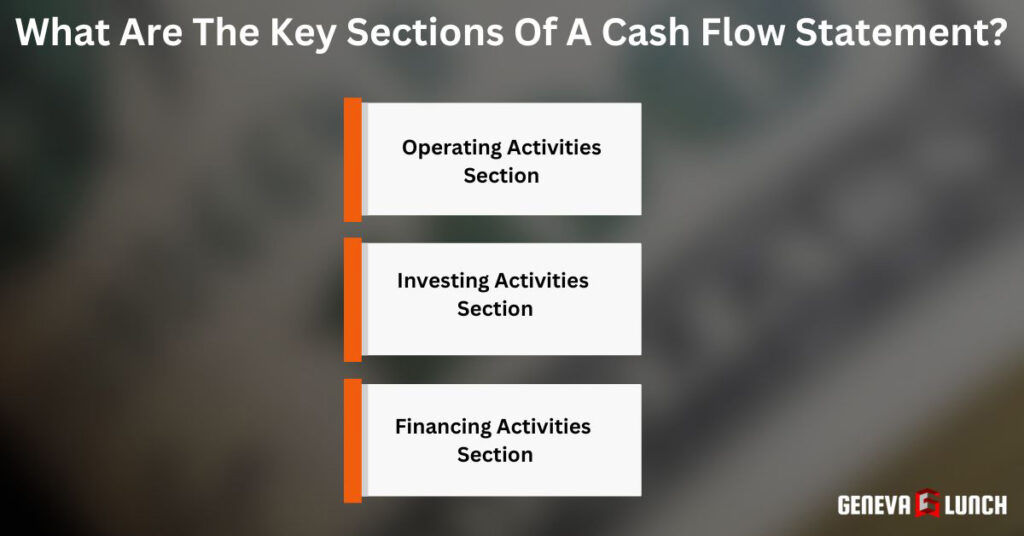
A cash flow statement has distinct sections. They give a complete view of an organization’s cash flow from various activities. Each section has a specific focus. Together, they reveal the business’s financial dynamics. The key sections include:
Operating Activities Section
This section of the cash flow statement shows cash flows from the company’s main business activities. It shows how much cash the company’s products or services generate. This is vital for assessing its ability to sustain and grow its operations. The primary components of this section include:
1. Cash Receipts From Customers
This refers to the cash customers receive for goods sold or services rendered. It is the main source of operational cash and a key indicator of the business’s ability to attract and keep customers.
2. Cash Payments To Suppliers And Employees
This includes all cash disbursed to suppliers for materials and employees for wages. These payments are vital to maintaining the company’s operations and workforce.
3. Cash Paid For Operating Expenses
This component covers cash spent on day-to-day operations. It excludes direct labor and material costs. It includes rent, utilities, and insurance. These expenses are vital to keep the business running. They often make up a large part of the operating activities outflows.
Investing Activities Section
The cash flow statement section shows the cash used or generated from investment activities. It reflects how the company allocates resources to support long-term growth and sustainability. The key areas within this section include:
1. Cash Transactions For Property, Plant, And Equipment
This category tracks cash spent on buying physical assets. These include buildings, machinery, and equipment. They must be used for a long time. It also includes proceeds from selling these types of assets. These transactions are crucial. They are major capital expenditures. They are also key indicators of the company’s long-term investment strategies.
2. Cash Transactions For Investments
It involves cash to buy or sell investment securities, like stocks and bonds. This category can include money invested in or received from subsidiaries, affiliates, or joint ventures. These transactions show how the company is managing its investments. They are outside its main business.
3. Cash Transactions For Assets
This includes cash flows from other long-term assets, like intangible assets (e.g., patents, trademarks) and long-term security deposits. These rare transactions can significantly impact the company’s finances and resource use.
Financing Activities Section
The financing activities section of the cash flow statement focuses on changes in the size and composition of the equity and debt of a company. This reflects how a company finances its operations and manages its financial structure. Here are the key activities typically reported under this section:
1. Issuing Shares
Issuing shares involves selling new shares to investors, a way for a company to raise equity capital. The proceeds from issuing shares are considered a cash inflow and are critical for financing new projects or paying down existing debt.
2. Payment Of Dividends
Dividends are payments made to shareholders from a company’s earnings. In the financing section, dividend payments represent a cash outflow, as cash goes out of the business to its owners. They reflect a company’s commitment to providing income to its shareholders.
3. Stock Buybacks
Stock buybacks, or repurchases, occur when a company returns its shares from the marketplace. This reduces the number of outstanding shares, potentially increasing the value of the remaining shares. Stock buybacks are cash outflows because they involve spending cash to purchase the company’s stock.
4. Issuing Bonds
Issuing bonds is a method for a company to raise debt capital. When a company issues bonds, it borrows money from the bond purchasers and agrees to pay back with interest. The proceeds from issuing bonds are recorded as cash inflows, providing significant liquidity that can be used for various corporate activities, including growth initiatives and refinancing old debt.
How Is A Cash Flow Statement Prepared?
Preparing a cash flow statement involves a series of steps. It shows how cash has entered and left the organization during a period and organizes financial data into a format that does this.
Gather Financial Statements
The first step in preparing a cash flow statement is to gather relevant financial statements, including the balance sheet, income statement, and any previous cash flow statements. These documents provide the data to track cash and cash equivalents changes and enable a true reflection of cash flows from operating, investing, and financing activities.
Determine The Reporting Period
Decide on the time frame for the cash flow statement. Depending on business needs or legal requirements, this could be a month, quarter, or year. The chosen reporting period will determine which transactions to review and ensure that all relevant cash flows are included in the statement for that time.
Choose The Method
The choice between the direct and indirect methods affects the cash flow from the operating activities report. Here’s an overview of each:
1. Direct Method
The direct method involves listing all cash receipts and payments, including cash received from customers and cash paid to suppliers and employees. This method gives a clear view of cash flows from operations, itemizing the specific sources and uses of money. It provides a transparent view of a company’s operating cash flows. This method is valued for its clarity and detail. However, it is more work to compile. It requires tracking all cash transactions.
2. Indirect Method
The indirect method starts with net income. It adjusts for non-cash transactions. These include depreciation, inventory changes, and accounts receivable and payable. This method is more common in practice. It is closely tied to the adjustments made on the accrual basis of accounting. The adjustments include adding back non-cash expenses. We also accounted for changes in balance sheet items. This gave us net cash from operating activities. This method is easier for companies that use accrual accounting. It requires less detailed tracking of cash transactions than the direct method.
Prepare The Statement
The prep starts by finding the cash flows from operating, investing, and financing. This involves:
- Operating Activities: Calculate net cash from operating activities. Adjust net income for items that affected it but didn’t involve some money. Adjustments include accounts receivable, inventory, accounts payable, depreciation, and amortization changes.
- Investing Activities: Identifying cash flows from acquiring and selling long-term assets. These include property, plant, equipment, and some investments not in cash equivalents.
- Financing Activities: Tracking flows related to changes in equity and company borrowings. This includes proceeds from issuing shares or bonds, repayments of borrowings, and payments to shareholders (dividends and buybacks).
Combine All Sections
Once each section is ready, the cash flows from operating, investing, and financing activities are combined. This calculates the total net increase or decrease in cash and cash equivalents for the period.
This combined figure reveals whether the company has generated enough cash to maintain and grow its operations or if it’s relying on external financing.
Reconcile With Beginning Cash
The last step in preparing a cash flow statement is reconciling the net cash change with the beginning cash balance. The company adds the net cash change to the beginning cash balance, giving the ending cash and cash equivalents for the period.
This ending balance should match the cash amount reported on the balance sheet at the end of the period. This reconciliation verifies the cash flow statement’s accuracy and shows how the cash position has changed.
What Are The Limitations Of A Cash Flow Statement?

A cash flow statement shows a company’s cash and liquidity. It has limits users should know when interpreting the results. Here are some key limitations:
Non-Cash Transactions Not Included
The cash flow statement only records actual cash transactions. It excludes non-cash items, like depreciation, amortization, and provisions, which can significantly affect a company’s financial position and results.
This exclusion can sometimes give an incomplete view of the company’s financial health. It omits significant non-cash transactions, like stock-based compensation and asset write-downs.
Timing Issues
The statement’s cash flows show the timing of actual cash transactions. Due to accrual accounting, they may not match the income statement’s earnings. This timing difference can make it hard to match cash flows to revenues and expenses, leading to misunderstandings about cash inflows and outflows.
Lack Of Detail On Future Cash Flows
The cash flow statement is great for past and present cash flows but doesn’t show future cash flows. This lack can be a significant limitation for investors and creditors who want to predict a company’s ability to generate cash and meet its future financial obligations.
Comparison Limitations With Other Companies
Comparing the cash flow statements of different companies can be challenging. This is due to differences in industry practices, the scale of operations, and accounting policies.
For example, different depreciation methods or financing structures can affect cash flow. This makes it hard to benchmark or evaluate performance accurately, which is key when comparing companies across different sectors or regions.
FAQ
How Does The Cash Flow Statement Differ From The Income Statement?
The cash flow statement records actual cash movements, highlighting a company’s liquidity. The income statement shows profitability by accounting for all revenues and expenses, regardless of cash transactions. The former tracks cash reality, whereas the latter follows accrual accounting principles.
Why Is The Cash Flow Statement Important?
The cash flow statement is vital as it details a company’s cash inflows and outflows. This transparency helps assess financial health, ensuring companies can cover debts and expenses. It’s indispensable for making strategic decisions and attracting investors by demonstrating fiscal responsibility.
How Does CapEx Impact The Cash Flow Statement?
Capital Expenditure (CapEx) affects the cash flow statement by showing a cash outflow in the investing activities section. This reflects money spent on acquiring or upgrading physical assets. Including capital expenditure highlights a firm’s investment into its operations and growth potential.
How Does Depreciation Affect The Cash Flow Statement?
Depreciation affects the cash flow statement by being added back to net income in the operating activities section. This adjustment is necessary because depreciation, while reducing taxable income, does not involve an actual cash outflow, thereby providing a clearer picture of cash flow.
How Can A Cash Flow Statement Help In Financial Forecasting?
A cash flow statement is instrumental in financial forecasting by detailing how cash enters and exits a business. It enables companies to predict future financial positions, ensure they have adequate cash reserves for operations and growth, and aid strategic planning and investment decisions.
How Often Should A Cash Flow Statement Be Updated?
A cash flow statement should ideally be updated quarterly to reflect a company’s liquidity and operational efficiency accurately. Regular updates help track financial health, ensure accurate budgeting, and aid stakeholders in making timely, informed decisions regarding business strategies.
Final Word
The cash flow statement is an indispensable financial tool for any business. It shows, in detail, how cash moves in and out of a company. It offers insights beyond what income statements or balance sheets can reveal.
By understanding this flow, businesses can better manage their operations. They can then invest wisely and keep enough cash to meet their obligations. A cash flow statement must track numbers.
However, it must also ensure financial stability and pave the way for future growth and success. Every business leader must prioritize accurate upkeep, as it is key to their company’s financial health and progress.