Financial Advisor: Types, Steps To Choose, Services They Offered
In today’s complex financial world, individuals and businesses face many challenges, from managing investments to planning for retirement. To handle these effectively, the expertise of a professional is often essential. This is where a financial advisor can be a crucial resource. But what exactly is a financial advisor?
A financial advisor is a professional who helps people manage their money. They offer advice on investments, savings, and financial planning to help people reach their financial goals. They assist with budgeting and retirement planning, ensuring you make informed decisions for your financial future.
This article will discuss what a financial advisor is. It covers what they do, the different types available, and the benefits of working with one.
Key Takeaways
- Defining Role: Financial advisors provide expert advice on investments, savings, and comprehensive financial planning.
- Goal Setting: They help individuals set and achieve their long-term financial goals.
- Personalized Strategies: Financial Advisors offer personalized strategies tailored to each client’s unique needs.
- Comprehensive Planning: They assist with retirement planning, estate planning, and tax strategies.
- Life Transitions: Financial advisors can guide you through major life changes and financial decisions.
What Is A Financial Advisor?
A financial advisor is a professional who helps you manage your money. They offer expert advice on how to save, invest, and ensure that your money grows over time. Their expertise covers a broad spectrum of financial activities which ranges from daily budgeting to strategic investing.
Importance Of Having A Financial Advisor
Having a financial advisor is crucial for achieving financial stability and securing your future. They bring clarity and precision to your financial planning, helping you understand how to manage your resources effectively. Here are several key benefits:
- Financial Planning: They help you create a plan to save and spend wisely. For instance, saving 10% of your income if you earn $50,000 a year.
- Goal Achievement: With professional advice, reaching goals like buying a home or securing a comfortable retirement becomes more achievable.
- Efficient Saving: They can guide you on how to build an emergency fund quickly and effectively.
What Does A Financial Advisor Do?
A financial advisor performs a variety of tasks to improve your financial health. They offer a variety of services to boost your financial health. So, if you’re curious to know more about exactly what does a financial advisor do, here are some of their key tasks:
- Budgeting: They assist in making a budget that fits your income and goals.
- Investing: Advisors suggest where to invest, like recommending $300 a month in a mutual fund, potentially growing to $115,580 in 20 years at a 6% growth rate.
- Debt Management: They offer strategies to reduce debt efficiently.
- Insurance Guidance: They help select the best insurance options to protect your financial future.
Types Of Financial Advisors
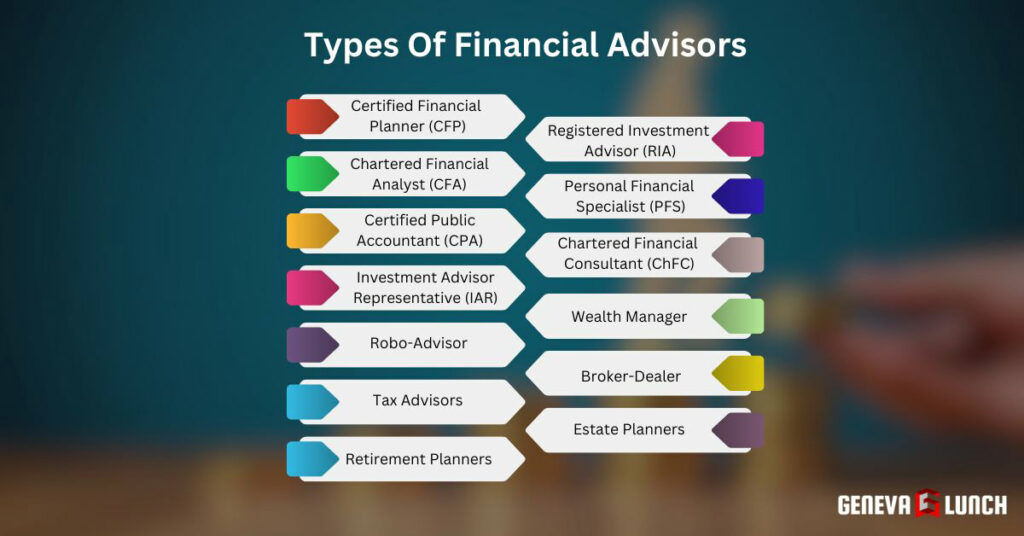
There are many different types of financial advisors, each with specific skills and areas of expertise. These professionals are trained to assist with various financial needs. Choosing the right type of financial advisor depends on your unique financial goals and needs. Here’s a closer look at some common types:
Certified Financial Planner (CFP)
Certified Financial Planners help you manage all areas of your financial life. They pass a rigorous exam and must adhere to high ethical standards.
A Certified Financial Planner assists with saving for retirement, investing wisely, and planning for future expenses like college or healthcare. They often create comprehensive plans that detail every aspect of your financial future.
Registered Investment Advisor (RIA)
Registered Investment Advisors focus primarily on investments. They are required to register with either state securities administrators or the Securities and Exchange Commission, depending on their size.
A Registered Investment Advisor can provide personalized advice on stocks, bonds, and other securities, tailored to meet your long-term financial goals.
Chartered Financial Analyst (CFA)
Chartered Financial Analysts are highly skilled in investment management and financial analysis. To earn the CFA designation, candidates must pass three challenging exams and gain relevant work experience.
Chartered Financial Analysts often work with large investment portfolios and provide detailed strategies for asset allocation and investment selection.
Personal Financial Specialist (PFS)
A Personal Financial Specialist is a Certified Public Accountant with additional certification in financial planning. PFS professionals offer more in-depth advice on a wide range of financial matters, including estate planning, retirement, and investments.
Personal Financial Specialists often integrate tax strategies to optimize financial outcomes.
Certified Public Accountant (CPA)
Certified Public Accountants are well-known for their expertise in accounting and tax matters. While primarily focused on ensuring accurate financial records and tax filing, many Certified Public Accountants also provide financial planning services.
They help clients understand the tax implications of their financial decisions.
Chartered Financial Consultant (ChFC)
Chartered Financial Consultants have completed extensive coursework in financial planning, similar to CFPs. However, their focus might include insurance, income taxation, retirement planning, and estate planning.
Chartered Financial Consultants do not need to pass a comprehensive board exam but are required to adhere to continuing education standards.
Investment Advisor Representative (IAR)
Investment Advisor Representatives are professionals who work for or under Registered Investment Advisors, providing advice on investments. To become an IAR, one must pass specific exams and comply with regulatory requirements.
Investment Advisor Representatives focus on tailoring investment portfolios to the client’s specific financial situation and goals.
Wealth Manager
Wealth managers serve high-net-worth individuals, offering a combination of financial planning and investment advice. They handle complex financial portfolios and provide comprehensive services that include tax planning, estate planning, and sometimes even legal guidance.
Wealth managers aim to preserve and grow wealth through strategic advice and management.
Robo-Advisor
Robo-advisors are digital platforms that provide automated, algorithm-based investment services with minimal human intervention. They are ideal for those seeking low-cost investment management.
Typically, Robo-Advisors offer portfolio management or advice based on mathematical algorithms developed from financial theories and historical data.
Broker-Dealer
Broker-dealers are licensed agents who buy and sell securities for their clients and themselves. They make the trade process smoother and help clients access various markets.
Broker-dealers must register with the SEC and are subject to both federal and state regulations.
Tax Advisors
Tax advisors specialize in tax law and planning. They provide advice on how to structure financial activities to minimize tax liabilities. Their services are crucial during tax season and for long-term planning.
Tax advisors ensure that clients achieve the best possible tax outcomes based on their financial decisions.
Estate Planners
Estate planners assist in the arrangement for the management and disposal of a person’s estate during life and after death. Their work includes drafting wills, setting up trusts, and planning for taxes.
Estate planners ensure that an individual’s assets are distributed according to their wishes while minimizing estate taxes.
Retirement Planners
Retirement Planners specialize in helping individuals plan for a financially secure retirement. They assess clients’ financial needs in retirement and devise strategies to meet these needs through savings, investments, and other income sources.
A retirement planner might help someone understand how much they need to save each month to retire comfortably based on their current age, income, and retirement goals.
Qualifications And Certifications
Qualifications and certifications are essential for financial advisors. They demonstrate a professional’s expertise and commitment to ethical practices. Below are details on the educational requirements, licensing, professional certifications, and regulatory compliance needed to become a financial advisor.
Educational Requirements
To become a financial advisor, one must start with a solid educational foundation. Most financial advisors hold at least a bachelor’s degree from a recognized university. The focus of their studies often includes subjects directly related to managing finances, understanding markets, or advising clients effectively.
Which Subject Is Best For Financial Advisor?
The best subjects for a financial advisor to study include finance, economics, accounting, or business. A degree in finance, for example, provides foundational knowledge about financial markets, investing, and financial planning. This education helps advisors understand how money works and how to manage it effectively.
Most financial advisors have at least a bachelor’s degree. For instance, studying finance can lead to an understanding of complex investment strategies that help clients grow their savings effectively.
Licensing
Licensing is crucial for financial advisors. Different types of advisors need different licenses. For instance, to sell insurance products, an advisor must have an insurance license. To give investment advice or manage client investment accounts, an advisor must pass exams like the Series 65 or Series 7, which are administered by regulatory bodies.
These licenses ensure that the advisor has a proper understanding of the products they are dealing with and complies with industry regulations.
Professional Certifications (E.g., CFP, CFA, ChFC)
Professional certifications like Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Chartered Financial Consultant (ChFC) are important. These certifications require passing rigorous exams and meeting continuing education requirements.
For example, a CFP must complete about 6,000 hours of financial planning experience. Holding such certifications demonstrates a high level of competency and dedication to providing quality financial advice.
Regulatory Compliance (E.g., SEC, FINRA)
Regulatory compliance is key for financial advisors. They must comply with regulations set by bodies like the Securities and Exchange Commission (SEC) and the Financial Industry Regulatory Authority (FINRA). These organizations ensure that financial advisors act in the best interests of their clients.
Compliance includes adhering to ethical standards, providing transparent investment advice, and regularly submitting financial reports. For instance, an advisor registered with the SEC must follow the strict guidelines that protect investors from fraud and unethical practices.
Services Offered By Financial Advisors

Financial advisors provide a variety of essential services. They help individuals manage their financial affairs efficiently. These services cater to different aspects of financial health. They can range from accumulating wealth to securing a comfortable retirement.
Financial Planning
Financial planning is a comprehensive service that covers every aspect of a client’s financial life. Advisors help clients assess their financial status, set realistic goals, and develop a strategy to achieve these goals.
For example, an advisor might assist a client in creating a budget that allocates $200 monthly towards an emergency fund, $300 to retirement savings, and $400 to pay down high-interest debt, ensuring a balanced approach to financial well-being.
Investment Management
This service involves the careful management of investments to maximize returns while minimizing risk. Financial advisors assess the client’s risk tolerance and financial goals to tailor a portfolio that could include stocks, bonds, mutual funds, and other investments.
They regularly review and rebalance the portfolio to maintain alignment with the client’s objectives, such as suggesting adjustments in response to economic changes or life events.
Retirement Planning
Retirement planning is crucial for securing a financially stable retirement. Advisors estimate how much money the client will need based on their desired retirement age and lifestyle, and they plan accordingly.
For example, an advisor might recommend setting aside $500 a month into a diversified retirement account that aims for a balance of growth and safety, anticipating a comfortable retirement.
Tax Planning
Tax planning involves strategies to reduce tax liabilities and maximize after-tax income. Financial advisors keep up-to-date with tax laws and recommend ways to take advantage of tax deductions, credits, and shelters.
An advisor may suggest making charitable donations or contributing to retirement accounts that offer tax benefits. This can help in effectively reducing the client’s taxable income.
Estate Planning
Estate planning ensures that a client’s assets are distributed as intended upon their death, while also minimizing tax impacts. Advisors may help set up trusts, draft wills, and plan for estate taxes to avoid legal complications and ensure that heirs receive their intended inheritances without excessive delay or taxation.
For example, setting up a trust may protect assets from probate and provide clear instructions for asset distribution.
Risk Management
Risk management involves analyzing financial risks and determining how to handle them effectively, often through insurance products. Advisors recommend policies like life, disability, and property insurance to protect against potential financial losses.
They may assess a client’s financial situation and recommend an appropriate level and type of insurance to safeguard their and their family’s future.
Education Planning
Advisors specializing in education planning help clients save for future educational expenses, using tools like education savings accounts or 529 plans.
For instance, if college costs for a child are projected to be $100,000, an advisor might recommend starting a savings plan that invests $500 a month in a tax-advantaged education account.
Debt Management
Debt management services focus on strategies to reduce and eliminate debt. Financial advisors analyze the interest rates, balances, and terms of all debts and advise on prioritization strategies, such as the debt snowball or avalanche methods.
They can also help negotiate with creditors to lower interest rates or consolidate debts into a single, more manageable payment, simplifying the client’s financial obligations and reducing overall interest costs.
How To Choose The Right Financial Advisor
Selecting the right financial advisor can greatly impact your financial security and future. It’s important to find someone who understands your financial goals and can work well with you. Here’s a step-by-step guide on how to find an advisor that meets your needs.
Step: 01) Assessing Your Needs And Goals
Start by clearly defining what you need from a financial advisor. Think about your financial goals, such as saving for a house, planning for retirement, or managing wealth.
For example, if you plan to buy a home in 10 years, you may need an advisor who is skilled in saving strategies and mortgage planning. This first step ensures you look for advisors who specialize in services that match your needs.
Step: 02) Understanding Fee Structures
Financial advisors can be paid in different ways, which affects their advice and your costs. Here are some common fee structures:
- Fee-only: These advisors charge a flat rate or a percentage of the assets they manage for you. For example, an advisor might charge 1% annually on your managed assets.
- Fee-based: Fee-based advisors charge a flat fee plus earn commissions from selling products.
- Commission-based: These advisors earn money when they sell you specific financial products.
Understanding these structures will help you find an advisor whose payment method aligns with your preferences.
Step: 03) Researching Credentials And Experience
Look for advisors who have strong credentials like CFP (Certified Financial Planner) or CFA (Chartered Financial Analyst). These certifications show they have passed exams and met ethical standards.
Also, check how long they’ve been in the business. Experience matters because a seasoned advisor has likely managed finances through different economic conditions.
Step: 04) Interviewing Potential Advisors
Once you have a few candidates, arrange interviews with them. This is your chance to see how well they understand your financial goals. Ask questions like, “How do you handle market downturns?” or “Can you provide an example of how you’ve helped someone in a similar financial situation?”
You may also ask how often they review investment portfolios and if they are available for regular check-ins.
Step: 05) Checking References And Reviews
After interviewing, ask for references from other clients, especially those who are in a similar financial situation to yours. Additionally, check online reviews to see what other clients say about their services. Reviews can reveal a lot about an advisor’s reliability and the quality of their service.
Benefits Of Working With A Financial Advisor

Working with a financial advisor offers many benefits that can help you secure and grow your financial resources more effectively. They offer tailored advice and strategic planning tailored to your specific financial situation. Here are some of the top benefits of engaging a financial advisor.
Personalized Financial Planning
A financial advisor provides personalized financial plans tailored to your unique financial situation and goals. For example, if your goal is to retire by age 65 with $1,000,000 in savings, an advisor can work backward to figure out how much you need to save each month.
They take into account your current age, income, expenses, and expected rate of return. This customized approach ensures that your financial actions are aligned with your long-term objectives.
Investment Expertise
Financial advisors have expert knowledge of investment products and markets. They can guide you on the best investment strategies to maximize returns while minimizing risks.
For example, an advisor might recommend diversifying your investment portfolio across different asset classes like stocks, bonds, and real estate, which can help reduce risk and improve potential returns over time.
Risk Management Strategies
Advisors help you identify potential financial risks and develop strategies to mitigate them. This might include recommending insurance products or setting up emergency funds.
For example, an advisor may suggest you maintain an emergency fund equivalent to six months of living expenses to protect against unexpected job loss or medical expenses.
Tax Optimization
Financial advisors can provide strategies to optimize your tax situation, ensuring you pay the minimum amount of taxes legally required. They stay updated on tax laws and can suggest ways to take advantage of tax deductions and credits.
For example, an advisor might advise contributing to a Roth IRA to benefit from tax-free growth and withdrawals in retirement.
Behavioral Finance Insights
Advisors use insights from behavioral finance to help you make better financial decisions. They can point out cognitive biases that might affect your investment decisions, such as the tendency to react impulsively to market fluctuations.
By understanding these biases, you can avoid common mistakes like selling stocks during a market dip, which can lead to losses.
Peace Of Mind And Confidence
Having a financial advisor can give you peace of mind and increase your confidence in your financial decisions. Knowing that a professional is managing your financial planning and investments allows you to focus on other aspects of your life without constant worry about your finances.
This can lead to better mental and emotional health, knowing that your financial future is in good hands.
Common Misconceptions About Financial Advisors
There are several common misconceptions about financial advisors that can prevent people from seeking their help. This might not always be in their best interest. Here’s a breakdown of these myths and the facts to dispel them:
Advisors Are Only For The Wealthy
Many believe that financial advisors are only necessary for very wealthy individuals. However, advisors can benefit anyone looking to improve their financial situation, regardless of income level.
For example, an advisor might help someone earning $40,000 a year create a budget, save for emergencies, and plan for retirement effectively. It proves that financial advice is not just for the rich.
Advisors Are Just Salespeople
It’s a common misconception that financial advisors are primarily focused on selling financial products. While some advisors do earn commissions on products they sell, many operate on a fee-only basis, meaning they earn no commission and their advice is unbiased.
For example, a fee-only advisor could recommend low-cost index funds that benefit the client’s long-term growth, rather than higher-commission products.
DIY Is Always Cheaper And Better
Some people think managing their finances themselves is always cheaper and more effective. While DIY financial management can save on advisory fees, it often lacks the expert knowledge and experience a professional brings.
For example, an advisor may use advanced tax strategies to save a client more money than they would pay in advisory fees, showing that professional advice can offer greater value.
All Advisors Offer The Same Services
Another misconception is that all financial advisors offer the same services. In reality, advisors specialize in different areas, such as retirement planning, tax advice, or wealth management.
For example, one advisor may specialize in helping clients with estate planning while another might focus on helping young professionals invest in the stock market. This illustrates the diverse range of services available.
Advisors Only Care About Selling Products
The idea that all advisors are primarily interested in selling products is misleading. Many advisors are bound by a fiduciary duty, which means they are legally required to act in their clients’ best interests.
For example, a fiduciary will recommend financial strategies and products that align with the client’s goals, even if it means less profit for themselves. It shows a commitment to the client’s well-being over sales.
Trends And Innovations In Financial Advisory Services
The financial advisory sector is evolving rapidly with new technologies and approaches to managing money. They are reshaping how financial advice is delivered. Here’s a closer look at some of the latest trends and innovations:
Technology Integration (E.g., AI, Big Data)
Technology plays a crucial role in modern financial advisory services. Artificial Intelligence (AI) and Big Data are used to analyze vast amounts of financial data quickly, leading to more informed and timely investment decisions.
For example, AI can predict market trends based on historical data, helping advisors recommend investments that align with these predictions.
Sustainable And Responsible Investing
Sustainable and responsible investing has gained popularity, focusing on investments in companies that prioritize environmental, social, and governance (ESG) criteria. Many investors now prefer their money to support sustainable practices.
For example, a financial advisor might help a client invest in a fund that only includes companies with strong environmental records, reflecting their values in their investment choices.
Behavioral Finance Techniques
Behavioral finance techniques are increasingly used to understand how psychological influences and emotional responses impact investors’ decisions. Advisors use these insights to help clients avoid common pitfalls like panic selling or excessive risk-taking.
For instance, an advisor can teach techniques to manage emotional reactions to market highs and lows, ensuring decisions are based on rational considerations rather than impulses.
Personalized Financial Apps And Tools
The rise of personalized financial apps and tools allows clients to manage their finances more actively and with greater customization. These apps provide real-time data, personalized insights, and scenario analysis, empowering users to make informed decisions.
For example, an app may analyze personal spending patterns and suggest ways to save more or highlight the impact of increasing monthly retirement contributions.
Virtual Advisory Services
Virtual advisory services have become more prevalent, particularly with the shift towards remote interactions. These services provide financial advice through digital platforms, allowing clients to consult with advisors from anywhere. This is particularly beneficial for clients who travel frequently or prefer online meetings.
An advisor may conduct a virtual meeting to discuss a client’s investment portfolio or plan for upcoming financial milestones, providing convenience and flexibility.
FAQs
Where To Find A Financial Advisor?
You can find a financial advisor through local banks, financial planning firms, or online platforms. Websites like the CFP Board also offer directories of certified advisors. Searching online for financial advisors in your area can yield a list of professionals along with reviews and ratings.
What Questions To Ask A Financial Advisor?
When meeting with a financial advisor, ask questions such as: What are your qualifications? How do you charge for your services? Can you provide examples of how you’ve helped clients achieve their financial goals? It will help you understand how they can cater to your specific financial needs.
When Do I Need A Financial Advisor?
You need a financial advisor when making major life decisions such as buying a house, saving for retirement, or managing inheritance. Also, if you feel overwhelmed by your finances or want to ensure you’re on the right path financially, consulting with a financial advisor can be beneficial.
Are Financial Advisors Safe?
Financial advisors are safe if they are properly licensed and adhere to regulatory standards. Choosing an advisor who is a fiduciary can add an extra layer of safety. Always check their credentials and registration with bodies like the SEC or FINRA before starting a relationship.
Is It Worth Paying For A Financial Advisor?
Paying for a financial advisor is worth it if you need expert guidance to manage your finances effectively. Advisors can help with complex financial planning, investment management, and tax strategies that can save you money and increase your assets over time. The benefits often outweigh the cost.
Can AI Replace Financial Advisor?
While AI can assist with many aspects of financial planning, it cannot fully replace a human financial advisor. Advisors provide personalized advice, emotional intelligence, and complex decision-making that AI currently cannot match. However, AI can be a useful tool to enhance the services provided.
Conclusion
Financial advisors play a vital role in helping individuals navigate the complexities of financial planning and investment management. By understanding the types of advisors available, knowing the right steps to choose one, and utilizing the diverse services they offer, you can make informed decisions about your finances. It will enhance your financial stability and growth.
Whether you’re planning for retirement, managing investments, or navigating life’s changes, a financial advisor can support you to achieve your financial goals.