How Much Does A Financial Advisor Cost? (Fees & Costs)
Financial advisors offer crucial guidance on investments, savings, and retirement planning, helping individuals optimize their financial strategies. Understanding the fees associated with their services is vital for anyone considering hiring one. So, how much does a financial advisor cost?
The cost of hiring a financial advisor typically ranges from 0.5% to 1.5% of the assets they manage annually. Some advisors offer services for a flat fee, ranging from $2,000 to $7,500 per year, or charge hourly rates from $100 to $400. The exact fee depends on their experience and services provided.
In this guide, we’ll discuss the specifics of financial advisor fees.
We’ll cover various fee structures, factors that influence these costs, and offer tips on choosing the right advisor for your financial situation.
Key Takeaways
- Percentage-Based Fees: Typical fees range from 0.5% to 1.5% of managed assets annually.
- Flat Fee Structure: Flat fee options generally vary between $2,000 to $7,500 per year.
- Hourly Rates: Hourly rates for financial advice range from $100 to $400.
- Fee Variability: Fee structure depends on services provided and advisor experience.
- Comprehensive Services: Higher fees may apply for more comprehensive financial planning services.
What Is A Financial Advisor?
A financial advisor helps people manage their money. They give advice on how to save, invest, and grow funds. Financial advisors can also help plan for retirement and other big life events. They understand the financial market well and can suggest the best options for your needs.
Importance Of Hiring A Financial Advisor
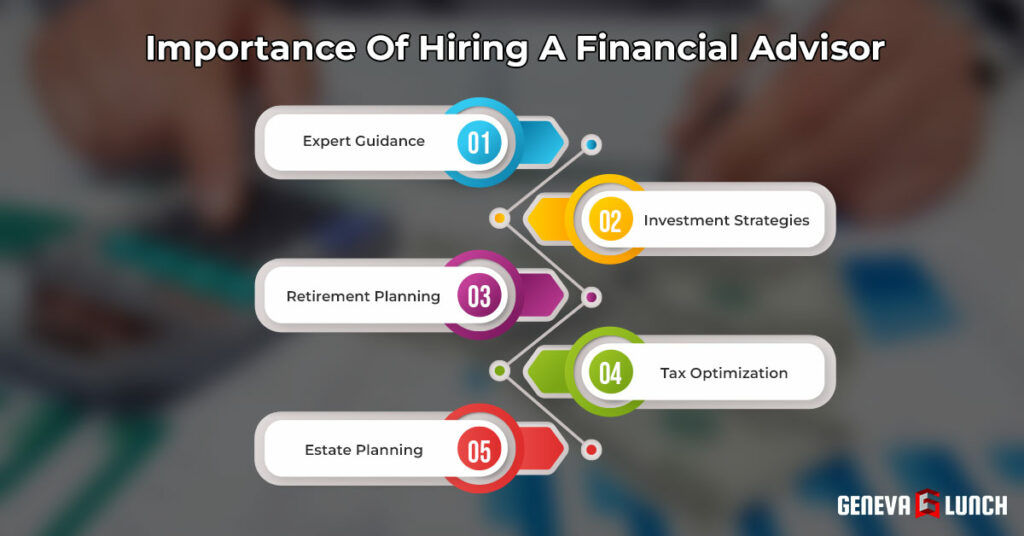
Hiring a financial advisor can be crucial for effective financial management. These professionals offer guidance that can help you navigate complex financial landscapes and make informed decisions. Here’s why hiring a financial advisor is important:
- Expert Guidance: Financial advisors provide professional advice tailored to your personal financial situation and goals.
- Investment Strategies: They help develop investment strategies that align with your risk tolerance and future objectives.
- Retirement Planning: Advisors assist in planning for retirement, ensuring you have a steady income later in life.
- Tax Optimization: They can offer strategies to minimize tax liabilities, maximizing your income and savings.
- Estate Planning: Advisors help in organizing your estate in ways that can benefit your heirs after your passing.
Factors Influencing Financial Advisor Costs
Choosing a financial advisor involves understanding the different factors that affect their fees. These factors can make the cost vary widely depending on who you work with and what you need from them. Here’s a closer look at what influences the cost of hiring a financial advisor.
Experience And Expertise
The level of experience and expertise a financial advisor has can significantly impact their fees. Typically, advisors with many years of experience and specialized knowledge in areas like estate planning or investments command higher fees.
For example, an advisor with over 20 years of experience may charge 2% of the assets they manage each year, compared to 1% for someone with less than five years of experience. This is because their extensive experience often leads to better financial outcomes for their clients.
Services Offered
The variety of services a financial advisor offers also affects their fees. Some advisors might only provide basic investment management, which could be less expensive. Others offer a full suite of services, including retirement planning, tax advice, and estate planning, which can increase the cost.
For instance, comprehensive services may cost you about $3,000 annually, while basic services might only be around $1,000.
Fee Structure
The way a financial advisor charges also plays a crucial role in the overall cost. Some advisors charge a flat fee for their services, others charge a percentage of the assets they manage, and some may even charge an hourly rate.
For example, if an advisor manages a portfolio worth $100,000 and charges a 1% fee, you would pay $1,000 per year. Understanding the fee structure is important to avoid surprises.
Location
Geographic location can influence how much you pay for financial advice. Advisors in larger, more expensive cities like New York or San Francisco typically charge more than those in smaller cities or rural areas due to higher business operating costs and living expenses.
An advisor in a major city might charge 20% to 30% more than one in a less expensive area.
Client’s Financial Situation
Finally, the complexity of your financial situation can affect how much you pay for an advisor’s services. Clients with more complex needs—such as those with multiple investment accounts, real estate holdings, or international assets—often face higher fees.
For example, a client with a complex portfolio might be charged 1.5% of their managed assets, compared to 1% for someone with a straightforward financial situation.
Types Of Fees Charged By Financial Advisors

Choosing a financial advisor also involves understanding the different types of fees they might charge. These fees can vary depending on the advisor’s payment structure and the services they provide. Below, we explore various fee structures and models to give you a clear understanding of what to expect.
Fee Structures
Fee structures tell you how financial advisors get paid for their services. This could be for the time spent, a set fee for a service, or based on how well your investments do. Knowing these will help you choose the right payment plan for your needs.
Hourly Fees
Hourly fees mean you pay the advisor based on the time they spend working with you. Typically, this might be something like $150 per hour. This structure is especially suitable if you only need occasional advice or have a specific, short-term financial question.
Flat Fees
A flat fee is a set amount charged for a particular service. For example, an advisor may charge $2,000 to create a detailed financial plan. This type of fee is transparent, making it easy to budget for, as you know the cost upfront without any surprises.
Retainer Fees
Retainer fees involve paying a regular fee, like monthly, to retain the advisor’s services. This might be around $500 per month and covers all the advice and management services provided within that period. It’s a common choice for those who require ongoing advice.
Percentage Of Assets Under Management (AUM)
This fee is calculated as a percentage of the total assets the advisor manages for you. For instance, if an advisor manages $100,000 and charges 1%, you would pay $1,000 annually. This fee model aligns the advisor’s incentive with your investment performance.
Commission-Based Fees
In this structure, advisors earn commissions based on products they sell or specific actions they take, like trading stocks. For example, they might get a 5% commission for selling a mutual fund.
This can lead to potential conflicts of interest, as advisors might favor products that give them higher commissions.
Performance-Based Fees
Advisors with performance-based fees earn more if your investments do well. For example, they might take 20% of the profits that exceed a certain benchmark.
This model encourages advisors to focus on high performance, but it may also encourage higher risk strategies.
Fee Models
Fee models explain the overall ways advisors can be paid, combining different structures or focusing on one main method. These models affect how advisors provide advice and their potential conflicts of interest. Let’s dive deeper into these models to help you choose the right one.
Fee-Only
Fee-only financial advisors are paid directly by their clients and do not receive any commissions from financial products. This might look like paying $3,000 annually for ongoing financial advice, with no additional fees or commissions. This model is highly transparent and minimizes conflicts of interest.
Fee-Based
Fee-based advisors mix a flat or hourly fee with the potential to earn commissions on products they sell. For example, you might pay an annual fee plus the advisor earns a commission if you purchase an insurance product they recommend. This model can create some conflicts of interest.
Commission-Only
Commission-only advisors do not charge you directly for advice; rather, they earn money from commissions on the financial products you buy through them. When you purchase a $100,000 annuity, the advisor might earn a 3% commission, or $3,000.
This structure heavily incentivizes product sales, which can lead to a higher potential for conflicts of interest.
Services Offered By Financial Advisors
Financial advisors offer a range of services to help you manage your money better. Each service targets different aspects of your financial health, from daily budgeting to long-term investment. Let’s discuss what each service entails and how it can benefit you.
Financial Planning
Financial planning involves creating a comprehensive plan that covers all areas of your finances, including saving, spending, investing, and protecting your assets. A financial advisor might help you set up a budget that allows you to save $200 a month, which could grow to $2,400 a year.
This service is essential for anyone looking to get their finances on track and achieve specific financial goals.
Investment Management
Investment management is about building and managing an investment portfolio that meets your long-term financial goals. An advisor will choose investments that match your risk tolerance and financial objectives.
For instance, if you invest $10,000, the advisor might help you achieve an average annual return of 5%, which would increase your investment to about $16,289 in ten years. This service is crucial for growing your wealth over time.
Retirement Planning
Retirement planning focuses on preparing for your financial needs after you stop working. A financial advisor can help you calculate how much money you need to retire comfortably and suggest ways to save that amount.
For example, they might recommend saving $500 a month in a retirement account that could grow to over $300,000 in 20 years, assuming a 5% annual return. This planning is vital to ensure you can enjoy your retirement years without financial worry.
Tax Planning
Tax planning involves strategies to minimize your tax liabilities and maximize your returns. Financial advisors can guide you on tax-efficient investments and help with deductions and credits.
For example, by investing in certain tax-advantaged accounts, you could save $1,500 in taxes each year. This service is beneficial for reducing your tax burden legally.
Estate Planning
Estate planning helps ensure that your assets are distributed according to your wishes after your death, while also minimizing estate taxes. An advisor might help you set up trusts and wills that protect your assets from excessive taxes and ensure they are passed on to your beneficiaries efficiently.
For example, proper estate planning could save your heirs thousands of dollars in potential estate taxes. This service is crucial for anyone wanting to leave a financial legacy to their loved ones.
How To Choose The Right Financial Advisor Based On Cost

Selecting the right financial advisor is crucial for managing your finances efficiently. Especially when you consider the costs involved. Here, you’ll find the steps to help you make an informed decision about which financial advisor is best for you based on cost.
Assessing Your Financial Needs
Firstly, clearly define what financial guidance you require. This could range from basic budgeting advice to more complex investment management or retirement planning. For instance, if you’re looking to invest a $50,000 inheritance, you’d benefit from an advisor skilled in investment strategies.
Knowing your needs helps you narrow down advisors who help you with financial planning for your specific needs. Thus, you can find advisors who specialize in those areas, ensuring you get the most relevant expertise.
Budgeting For Advisor Fees
Determine how much you’re willing to spend on financial advisory services. Establish a clear budget for these fees to avoid overspending. For example, if you have a portfolio worth $200,000 and you decide you can afford a 1% fee, you should plan to spend about $2,000 per year on advisory services.
This budgeting step is essential to keep your financial goals on track without undue strain from advisory costs.
Comparing Multiple Advisors
Comparing different financial advisors is crucial to finding one that offers the best value and meets your specific financial needs. Each advisor has a unique approach, expertise, and fee structure. This makes it important to evaluate several options before making a decision.
Initial Consultations
Take advantage of initial consultations, which are often free, to discuss each advisor’s approach and fee structure. For example, during these meetings, ask direct questions like whether they charge by the hour, a flat fee, or a percentage of assets managed. This will help you understand if their fee structure aligns with your budget.
Fee Transparency And Disclosure
Only consider advisors who are transparent about their fees. They should provide a clear breakdown of what their charges cover and how they calculate them. This transparency ensures there are no hidden costs. This will save you from potential surprises later.
Understanding The Scope Of Services
Ensure that you fully understand what services are included in the fees quoted by the advisor. For instance, if an advisor charges $3,000 annually, confirm whether this includes just investment management or additional services like tax planning or estate planning.
Knowing exactly what you’re paying for helps you assess the value they are offering.
Negotiating Fees
Don’t hesitate to negotiate the fees with an advisor. Especially if you are bringing a substantial amount of business or a long-term engagement, you might get a reduced rate. For example, if an advisor typically charges 1.5% of assets under management, you might negotiate the rate down to 1.25% by committing to a multi-year relationship.
Effective negotiation can lead to significant savings over the duration of your financial planning.
Ways To Reduce The Cost Of Financial Advisory Services
Financial advice can be essential but also expensive. However, there are several strategies you can use to reduce the cost of these services without sacrificing the quality of the advice you receive. Here’s how you can manage your finances effectively while keeping costs down.
Choosing A Fee-Only Advisor
Opting for a fee-only advisor can often lead to lower overall costs compared to advisors who earn commissions. Fee-only advisors charge directly for their services without earning commissions from selling products. This can lead to more straightforward, unbiased advice.
For example, if a fee-only advisor charges a flat rate of $2,500 per year, you might save money compared to paying a percentage of your assets under management, which could add up to more as your portfolio grows.
Using A Robo-Advisor
Robo-advisors are automated investment platforms that provide financial advice based on algorithms. They are typically much cheaper than human advisors.
For instance, a robo-advisor might charge 0.25% of your assets each year. When you have $40,000 in investments, that’s only $100 per year, which is far less than what most human advisors charge.
Bundling Services
You can also save money by bundling multiple services with the same advisor. Some advisors offer package deals if you choose them for several services like investment management, retirement planning, and tax advice.
For example, separately, these services might cost $1,000 each per year, but bundled together, they might only cost $2,500, saving you $500.
Leveraging Employer-Provided Financial Advisory Services
Many employers offer financial advisory services as part of their benefits package. These services are usually provided at a reduced cost or even for free. Taking advantage of this can significantly lower your expenses for financial planning.
For instance, if your employer offers free access to a financial advisor, you can get the advice you need without any direct cost to you, which would otherwise be a substantial expense if sourced independently.
Additional Considerations When Choosing A Financial Advisor

When selecting a financial advisor, there are several crucial factors you should consider. This is to ensure you find someone who is trustworthy, suits your financial needs, and operates within legal standards. Here are some of the key considerations:
Fiduciary Responsibility
Choosing a financial advisor who has a fiduciary responsibility is vital. This means they are legally obliged to put your interests ahead of their own. For example, if two investments offer similar benefits, but one offers the advisor a higher commission, a fiduciary would still recommend the one that’s best for you, not the one that pays them more.
This commitment protects you from conflicts of interest and ensures your advisor’s advice is always aimed at benefiting you.
Regulatory Compliance And Licenses
Make sure your financial advisor complies with all regulatory requirements and holds appropriate licenses. This is a guarantee that they meet professional standards and are recognized by regulatory bodies like the Securities and Exchange Commission (SEC) or the Financial Industry Regulatory Authority (FINRA).
For instance, an advisor registered with the SEC is subjected to periodic inspections and must adhere to strict financial and ethical standards.
Reputation And Reviews
The reputation of a financial advisor is a strong indicator of their reliability and the quality of their service. Spend time checking online reviews, testimonials, and possibly even news articles about the advisor or their firm.
An advisor with a long track record of positive reviews and few client complaints is more likely to provide satisfactory service.
Personal Chemistry And Compatibility
The personal connection you have with your financial advisor is crucial. You need to feel comfortable and trust them, as you’ll be sharing detailed personal and financial information. When you find that you’re uncomfortable during initial consultations, or if your personalities don’t mesh well, it’s worth continuing your search.
Good chemistry can enhance communication and make financial planning more effective.
Services Offered And Specializations
It’s important to choose an advisor whose specializations align with your financial needs. For example, if you’re interested in investing in stocks, an advisor who specializes in stock market investments is preferable.
Similarly, if you need retirement planning, someone with expertise in this area will be more beneficial. Make sure the advisor you choose has experience and knowledge in the specific services you require.
Transparency And Communication
Clear and consistent communication is essential when working with a financial advisor. They should be transparent about their methods, how they’re compensated, and any potential conflicts of interest. Also, it’s important that they communicate regularly and in a way that you understand.
For example, an advisor should explain investment choices clearly and provide regular updates about your portfolio’s performance. This transparency will help build trust and ensure that you are well-informed about your financial decisions.
FAQs
What Is The Average Cost Of A Financial Advisor?
The average cost of a financial advisor can vary. Typically, advisors charge between 0.5% to 2% of the assets they manage annually. Some charge a flat fee, ranging from $2,000 to $7,500 per year. Hourly rates can also be an option which is generally between $100 to $400 per hour.
What Is The Normal Fee For A Financial Advisor?
The normal fee for a financial advisor usually ranges from 0.5% to 1.5% of the assets under management (AUM) annually. This means if you have a $100,000 portfolio, a 1% fee would equal $1,000 per year. Advisors may also offer flat or hourly fees depending on the services you need.
Is 2% Fee High For A Financial Advisor?
Yes, a 2% fee is considered high for a financial advisor. Most advisors typically charge between 0.5% to 1.5% of the assets under management annually. A fee of 2% can significantly impact your investment returns over time. For large portfolios, it may reduce the overall growth of your investments.
Are Financial Advisor Fees Tax-Deductible?
No, financial advisor fees are not tax-deductible. This means that you cannot reduce your taxable income by the amount you pay for these services. Previously, it was possible to deduct some financial advisory fees if they exceeded a certain portion of your income, but this is no longer allowed.
Is It Worth Paying A Financial Advisor?
Paying a financial advisor can be worth it if you need expert guidance with your finances. Financial advisors can help you create a solid financial plan, and manage investments wisely. They can also help with specific financial goals. Their expertise makes financial advisors worth the investment.
What Questions Should I Ask a Potential Financial Advisor?
When meeting a financial advisor, ask about their qualifications, experience, and specific services they offer. Questions like, “Are you a fiduciary?” and “How do you get paid?” are crucial. Also inquire about their typical client profiles to ensure they are well-suited to your financial situation.
Conclusion: How Much Does A Financial Advisor Cost
In conclusion, the cost of hiring a financial advisor varies widely based on their fee structure, experience, and the type of services they provide. Whether you opt for a percentage-based fee, a flat fee, or hourly rates, it’s important to choose an advisor who offers transparent pricing and tailored advice that meets your financial goals. Remember, investing in quality financial advice can yield significant benefits for your financial future.