Registered Investment Advisor (RIA): Qualifications & Core Services
Managing money wisely is important for achieving financial goals. Many people seek professional help to navigate investments and financial planning. One key professional in this field is the Registered Investment Advisor (RIA). So, what is a Registered Investment Advisor (RIA)?
A Registered Investment Advisor (RIA) is a person or firm that gives advice about investments. They must register with the SEC or state regulators. RIAs follow strict rules to act in the best interest of their clients. They charge fees for their services and help with financial planning.
In this guide, we’ll explore what RIAs do, how they work, and their qualifications. We’ll also discuss the benefits of working with an RIA, the challenges they face, and future trends in the industry.
Key Takeaways
- Core Function: Registered Investment Advisors (RIAs) give professional investment advice to individuals and businesses.
- Regulatory Compliance: RIAs must register with the SEC or state regulators to operate legally.
- Fiduciary Duty: They follow strict rules to act in the best interest of their clients.
- Personalized Services: RIAs provide personalized financial planning and charge fees for their services.
- Fee Structures: They charge flat fees, hourly rates, or a percentage of assets managed.
What Is A Registered Investment Advisor (RIA)?
A Registered Investment Advisor (RIA) is a person or firm that provides investment advice. RIAs register with the SEC or state regulators and need to follow strict rules to protect clients. They act in the best interest of their clients, helping them make informed investment decisions.
What Does Registered Investment Advisor (RIA) Do?
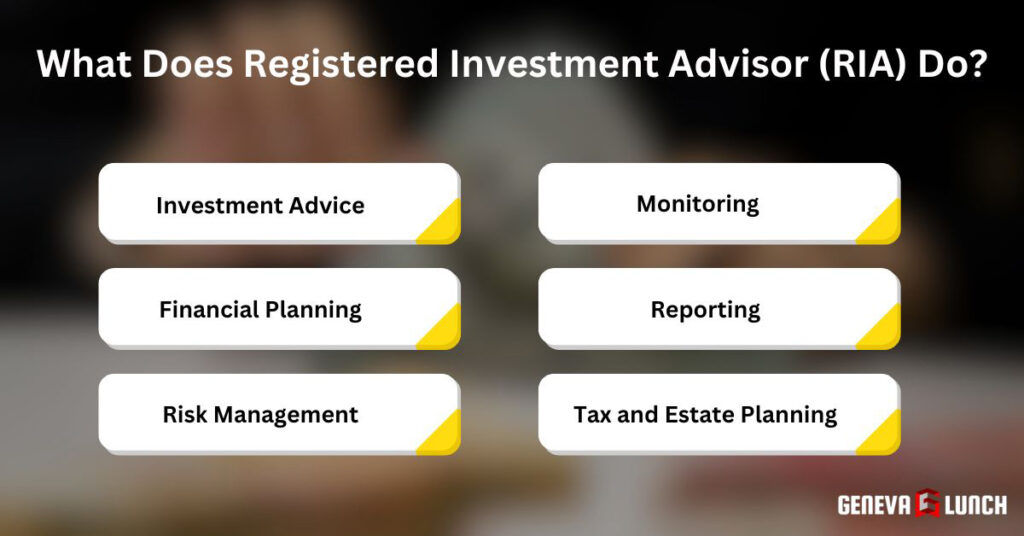
A Registered Investment Advisor (RIA) helps people and companies manage their investments. They provide advice and create plans to meet financial goals. Here’s what they do:
- Investment Advice: Guide clients on stocks, bonds, and other investments.
- Financial Planning: Create plans for retirement, college savings, and other goals.
- Risk Management: Help clients understand risks and returns.
- Monitoring: Track investments and adjust strategies as needed.
- Reporting: Provide regular updates on investment performance.
- Tax and Estate Planning: Assist with strategies to minimize taxes and plan for the future.
RIA Qualifications And Requirements
Registered Investment Advisors (RIAs) need specific qualifications and must meet certain requirements. These ensure they have the knowledge and skills to help clients with their investments. Qualifications and requirements include educational background, licensing and registration, and examination requirements.
Educational Background
Education is crucial for RIAs. It helps them understand financial markets and investment strategies. Having the right education ensures that RIAs can provide the best advice to their clients. There are specific degrees and certifications that are particularly relevant.
Relevant Degrees
Many RIAs have a degree in finance, economics, or business. A bachelor’s degree in these fields is common. These degrees teach important skills like analyzing financial data and understanding markets.
Some RIAs go further and get advanced degrees. An example is a Master of Business Administration (MBA). This degree provides deeper knowledge of business and finance. Having a relevant degree helps RIAs give better advice to their clients.
Certifications
RIAs often have certifications that show their expertise. The Certified Financial Planner (CFP) is one popular certification. To get a CFP, an RIA must pass a tough exam and have work experience. Another common certification is the Chartered Financial Analyst (CFA).
The CFA also requires passing several exams and having work experience. These certifications prove that an RIA has the skills and knowledge to manage investments well.
Licensing And Registration
Licensing and registration are required for RIAs to operate legally. These steps ensure that RIAs meet specific standards and are qualified to provide investment advice. Licensing and registration are overseen by federal and state authorities. This helps protect clients and maintain trust in the financial system.
SEC Registration
RIAs who manage over $100 million must register with the SEC. The SEC is the federal agency that oversees financial markets. Registering with the SEC involves filling out forms and providing detailed information about the RIA’s business.
This includes information about the RIA’s investment strategies and fees. SEC registration helps ensure that the RIA follows federal laws and regulations.
State Registration
RIAs who manage less than $100 million register with state regulators. Each state has its own rules and procedures for registration. RIAs must follow the regulations of the state where they operate.
This may include providing information about their business and passing a background check. State registration helps protect investors by making sure RIAs meet certain standards.
Examination Requirements
Examinations are a crucial part of becoming an RIA. They test the knowledge and skills necessary to provide sound investment advice. Passing these exams shows that the RIA understands important concepts and regulations. There are specific exams that RIAs must pass to become qualified.
Series 65
The Series 65 exam is necessary for most RIAs. This test covers laws, regulations, and ethics related to investments. It also includes questions on investment strategies and products. Passing the Series 65 exam allows RIAs to provide investment advice for a fee.
The exam ensures that RIAs understand important financial principles and can act in their clients’ best interests.
Series 66
Some RIAs take the Series 66 exam instead. This exam combines the content of the Series 63 and Series 65 exams. It covers laws, regulations, ethics, and investment topics.
The Series 66 exam is often taken by those who already hold certain other licenses, like the Series 7. Passing the Series 66 exam allows an RIA to provide investment advice and execute transactions for clients.
How To Become A Registered Investment Advisor
Becoming a Registered Investment Advisor (RIA) involves several steps. These steps include getting the right education, completing certifications and licensing, and passing exams. Each step is important to ensure that the advisor is well-prepared to help clients with their investments.
Educational Path
The first step to becoming an RIA is education. Most RIAs start with a bachelor’s degree. Common fields of study are finance, economics, or business. For example, a degree in finance teaches about stocks, bonds, and other investments.
Some RIAs also pursue advanced degrees. A Master of Business Administration (MBA) can provide deeper knowledge in business management. Having a strong educational background is important. It helps the RIA understand complex financial concepts and strategies.
Certification And Licensing Process
After completing their education, RIAs need to get certified and licensed. Certifications show that the RIA has special skills and knowledge. Popular certifications include Certified Financial Planner (CFP) and Chartered Financial Analyst (CFA).
To get these certifications, RIAs need to pass exams and have work experience. Licensing is also necessary. RIAs who manage over $100 million register with the SEC. Those managing less than $100 million register with state regulators. Both certifications and licensing ensure that the RIA is qualified to give investment advice.
Exams And Qualifications
Passing exams is a crucial part of becoming an RIA. These exams usually test the knowledge and skills needed to provide investment advice. They cover topics like laws, regulations, and ethics.
Building Experience
Gaining experience is important for RIAs. Experience helps them understand real-world financial situations. Many RIAs start by working in finance or related fields.
For example, they might work as financial analysts or planners. This experience is valuable. It helps the RIA learn how to manage investments and advise clients effectively.
Internships
Internships are another way to gain experience. Many RIAs do internships while they are still in school. Internships provide hands-on training in investment firms. They allow future RIAs to learn from experienced professionals.
For example, an internship might involve researching stocks or creating financial plans. Internships help build the practical skills needed to become a successful RIA.
Regulatory Environment
The regulatory environment for Registered Investment Advisors (RIAs) ensures that they follow laws and rules. These regulations protect investors and maintain trust in the financial system. There are key regulations and acts that RIAs must follow to ensure they act in their clients’ best interests.
Role Of The SEC
The Securities and Exchange Commission (SEC) plays a big role in regulating RIAs. RIAs who manage over $100 million must register with the SEC. The SEC makes sure that RIAs follow federal laws and rules.
It checks that RIAs provide honest and clear information to their clients. The SEC also investigates complaints and takes action against RIAs who break the rules. This helps protect investors from fraud and dishonest practices.
Role Of State Regulators
State regulators oversee RIAs who manage less than $100 million. Each state has its own set of rules and procedures. State regulators ensure that RIAs meet local requirements. They also monitor the activities of RIAs within the state.
For example, an RIA in California must follow California’s specific rules. State regulators help protect investors by checking that RIAs are qualified and follow the laws. They handle complaints and can take action against RIAs who do not comply.
Key Regulations And Acts
There are several key regulations and acts that RIAs need to follow. These laws set the standards for how RIAs should operate. They ensure that RIAs act in the best interests of their clients.
Investment Advisers Act Of 1940
The Investment Advisers Act of 1940 is a key law for RIAs. It requires RIAs to register with the SEC or state regulators. The Act sets rules for how RIAs must treat their clients.
For example, RIAs must provide honest advice and disclose any conflicts of interest. This law helps protect investors from fraud and ensures that RIAs act fairly.
Dodd-Frank Act
The Dodd-Frank Act was passed in 2010 to improve financial regulation. It increased the oversight of financial firms, including RIAs. The Act requires RIAs to register with the SEC if they manage more than $100 million.
It also introduced more rules to protect investors. For example, it requires RIAs to keep better records and report more information to regulators. This helps ensure transparency and accountability in the financial industry.
MiFID II
MiFID II stands for the Markets in Financial Instruments Directive II. It is a set of rules from the European Union that took effect in 2018. MiFID II applies to RIAs who operate in Europe. It aims to increase transparency and protect investors.
The rules require RIAs to provide detailed reports on their fees and services. They also must disclose any conflicts of interest. MiFID II helps ensure that RIAs act in the best interests of their clients in the European market.
Core Services Provided By RIAs

Registered Investment Advisors (RIAs) offer many important services. These services help clients manage their money and plan for the future. RIAs provide investment management, financial planning, and wealth management. Each of these services includes several key activities that benefit clients.
Investment Management
Investment management is a core service provided by the Registered Investment Advisors (RIAs). They help clients make smart investment choices. This can involve creating and managing a portfolio of investments.
Portfolio Construction
Portfolio construction involves selecting a mix of investments. RIAs choose stocks, bonds, and other assets for the client’s portfolio. For example, an RIA might create a portfolio with 60% stocks and 40% bonds. This helps balance risk and return.
The goal is to create a diversified portfolio that meets the client’s financial goals. Diversification reduces the risk of losing money. A well-constructed portfolio can provide steady growth over time.
Asset Allocation
Asset allocation is the process of dividing investments among different categories. RIAs decide how much to invest in stocks, bonds, and other assets. For example, they might allocate 50% to stocks, 30% to bonds, and 20% to real estate.
This strategy helps manage risk. By spreading investments across various assets, RIAs can reduce the impact of a poor-performing asset. Asset allocation is based on the client’s risk tolerance and financial goals.
Risk Management
Risk management involves identifying and reducing investment risks. RIAs assess the risk level of different investments. They make sure the client’s portfolio matches their risk tolerance. For example, an RIA might reduce stock investments if the client prefers low risk.
RIAs use strategies like diversification to minimize risk. Risk management is important to protect the client’s money and ensure steady growth. RIAs regularly review and adjust the portfolio to manage risk effectively.
Financial Planning
Financial planning is another key service offered by the Registered Investment Advisors (RIAs). They help clients plan for important financial goals. This can include retirement, estate, and tax planning.
Retirement Planning
Retirement planning involves creating a plan to save for retirement. RIAs help clients determine how much money they need to retire comfortably. They suggest investment strategies to reach this goal. For example, they might recommend saving $500 per month in a retirement account.
RIAs help choose the right retirement accounts, like 401(k)s or IRAs. RIAs monitor the progress and adjust the plan as needed. Retirement planning ensures clients can enjoy a secure and comfortable retirement.
Estate Planning
Estate planning involves preparing for the transfer of assets after death. RIAs help clients create wills and trusts. They also advise on how to minimize estate taxes. For example, an RIA might help a client set up a trust to pass on $1 million to their children.
RIAs ensure that the client’s wishes are carried out. Estate planning protects the client’s assets and reduces the tax burden on heirs. It provides peace of mind knowing that the client’s family is taken care of.
Tax Planning
Tax planning involves finding ways to reduce taxes. RIAs help clients take advantage of tax deductions and credits. They also suggest investment strategies to minimize tax liabilities. For example, they might recommend investing in tax-free municipal bonds.
RIAs plan for both short-term and long-term tax savings. Effective tax planning can save clients a significant amount of money. RIAs keep up with tax laws and regulations to provide the best advice.
Wealth Management
Wealth management is a comprehensive service provided by the Registered Investment Advisors. It includes managing all aspects of a client’s financial life. This involves cash flow, debt, and insurance planning.
Cash Flow Management
Cash flow management involves tracking income and expenses. RIAs help clients create budgets and manage their spending. For example, they might suggest saving 20% of income each month.
RIAs help clients understand where their money is going. By managing cash flow, clients can save more and reduce unnecessary expenses. This ensures that clients have enough money for their needs and future goals.
Debt Management
Debt management involves creating a plan to pay off debt. RIAs help clients prioritize their debts and find the best repayment strategies. For example, they might advise paying off high-interest credit card debt first.
RIAs help clients understand the impact of debt on their finances. By managing debt, clients can improve their financial health. RIAs also help clients avoid taking on new debt unnecessarily.
Insurance Planning
Insurance planning involves evaluating and selecting insurance policies. RIAs help clients choose the right coverage for their needs. This includes life, health, and property insurance. For example, they might recommend a life insurance policy with a $500,000 benefit.
RIAs ensure that clients are protected against financial loss due to unforeseen events. Proper insurance planning provides peace of mind and financial security. RIAs review policies regularly to ensure they continue to meet the client’s needs.
RIA Compensation Models
Registered Investment Advisors (RIAs) have different ways to get paid. These are called compensation models. They help clients understand how much they will pay for services. Each model has its own method of charging fees. It is important for clients to know these models to choose the best advisor for their needs.
Fee-Only
Fee-only advisors charge clients a flat fee or hourly rate. They do not earn commissions from selling products. For example, an RIA might charge $200 per hour for their services. This model reduces conflicts of interest.
Clients know that the advice is unbiased. Fee-only advisors only get paid by the client. This makes it clear how much the client is paying for the advice. The fee-only model is clear and simple.
Commission-Based
Commission-based advisors earn money by selling financial products. They get a commission for each product sold. For example, an RIA might earn 3% for selling a mutual fund. This can create a conflict of interest.
The advisor may suggest products that earn higher commissions. Clients need to be aware of this potential bias. This model can make it hard to know the true cost of advice. Clients should ask about commissions before making decisions.
Fee-Based
Fee-based advisors charge both fees and commissions. They might charge a flat fee for advice and earn commissions on products. For example, an RIA might charge a $1,000 flat fee plus commissions on investments. This model combines fee-only and commission-based methods.
Clients pay for advice and for product purchases. It is important to understand both parts of the payment. Clients should ask how much they will pay in total. This helps avoid surprises.
Percentage Of AUM (Assets Under Management)
Advisors using this model charge a percentage of the assets they manage. For example, an RIA might charge 1% of the total assets each year. When they manage $1,000,000, the fee would be $10,000 annually. This model aligns the advisor’s interests with the client’s.
The advisor earns more when the client’s assets grow. It encourages good performance and careful management. Clients should understand how the percentage is calculated. This helps them know what they are paying.
Retainer Fees
Retainer fees involve regular payments for ongoing services. Clients pay a set amount each month or year. For example, an RIA might charge $500 per month for continuous advice and support. This model provides steady income for the advisor.
This ensures that clients receive consistent attention. Retainer fees cover various services like planning and investment management. Clients know they will get regular help. This can make financial planning easier.
How To Choose An RIA
Choosing a Registered Investment Advisor (RIA) is an important decision. It can impact your financial future. There are several steps to find the right advisor. These include checking credentials, evaluating experience, understanding fee structures, and assessing compatibility.
Checking Credentials
The first step is to check the RIA’s credentials. Look for relevant degrees and certifications. Common certifications are Certified Financial Planner (CFP) and Chartered Financial Analyst (CFA). These show that the advisor has the necessary education and skills.
Also, verify that the RIA is registered with the SEC or state regulators. You can check this information online. Checking credentials ensures that the advisor is qualified to give financial advice.
Evaluating Experience
Next, evaluate the advisor’s experience. Ask how long they have been working as an RIA. Experienced advisors have handled various financial situations. This helps them provide better advice.
For example, an advisor with 10 years of experience might have more insights than a new advisor. Also, ask about their experience with clients like you. When you need retirement planning, find an advisor who specializes in that area. Evaluating experience helps ensure the advisor can meet your specific needs.
Understanding Fee Structures
It is important to understand how the advisor gets paid. Ask about their fee structure. Do they charge a flat fee, hourly rate, or a percentage of assets? Knowing this helps you understand the total cost.
For example, an RIA might charge 1% of assets under management. When you have $500,000, the fee would be $5,000 per year. Make sure you are comfortable with the fee structure. Understanding fees helps avoid surprises later.
Assessing Compatibility
Finally, assess your compatibility with the advisor. Schedule a meeting to see if you feel comfortable with them. Good communication is key. Ask if they are willing to answer your questions and explain things clearly. You should feel that the advisor understands your goals and concerns.
Compatibility is important for a long-term relationship. A good advisor listens to you and works in your best interest. Assessing compatibility ensures a good working relationship.
Advantages Of Working With An RIA

Working with a Registered Investment Advisor (RIA) offers many benefits. These advisors help manage your money and plan for the future. There are several key advantages to consider. Understanding these benefits can help you decide if an RIA is right for you.
Fiduciary Responsibility
RIAs have a fiduciary responsibility to their clients. This means they must act in your best interest. They provide honest and unbiased advice. For example, an RIA needs to recommend investments that are best for you, not ones that make them more money.
This protects you from conflicts of interest. Fiduciary responsibility ensures that your advisor is working to help you achieve your financial goals.
Personalized Advice
RIAs offer personalized advice tailored to your needs. They take the time to understand your financial situation. For example, they consider your income, expenses, and future goals. Based on this information, they create a customized financial plan.
This plan can include saving for retirement, buying a home, or paying for college. Personalized advice helps you make better financial decisions.
Comprehensive Financial Planning
RIAs provide comprehensive financial planning. They look at all aspects of your finances. This includes investments, taxes, insurance, and estate planning.
For example, an RIA can help you create a retirement plan, manage your investments, and minimize your taxes. Comprehensive planning ensures that all parts of your financial life work together. This helps you reach your financial goals more effectively.
Transparent Fee Structure
RIAs have a transparent fee structure. They clearly explain how they get paid. This can include flat fees, hourly rates, or a percentage of assets under management.
For example, an RIA might charge 1% of the assets they manage. When you have $100,000, the fee would be $1,000 per year. Transparent fees help you understand the cost of services. This ensures there are no hidden charges.
Long-Term Relationship
Working with an RIA can lead to a long-term relationship. They provide ongoing support and advice. For example, an RIA can help you adjust your financial plan as your life changes.
They stay with you through different stages of life, such as buying a house or retiring. A long-term relationship ensures that your financial plan evolves with your needs. This provides stability and continuity in managing your finances.
Challenges And Risks In The RIA Industry
The RIA industry faces several challenges and risks. These can impact how advisors do their jobs and serve their clients. It is important to understand these challenges to better navigate the industry. Key challenges include regulatory changes, market volatility, competition from robo-advisors, client retention, and operational risks.
Regulatory Changes
Regulatory changes are a major challenge for RIAs. New laws and rules can affect how they operate. For example, changes in SEC regulations may require RIAs to update their practices. Keeping up with these changes can be difficult.
RIAs need to stay informed about new regulations to remain compliant. This can require additional time and resources. Regulatory changes can also impact the cost of providing services.
Market Volatility
Market volatility is another significant risk. The value of investments can go up and down quickly. For example, a sudden drop in the stock market can reduce the value of a client’s portfolio. RIAs must help clients manage these risks.
They need to create strategies to protect against losses. Market volatility can make it hard to achieve steady growth. Clients may become anxious during volatile periods, requiring extra communication and reassurance from RIAs.
Competition From Robo-Advisors
Competition from robo-advisors is growing. Robo-advisors are automated online platforms that provide investment advice. They often charge lower fees than human advisors. This can attract clients looking to save money.
RIAs must highlight the benefits of personalized service to compete. They offer tailored advice and a personal touch that robo-advisors cannot match. RIAs need to differentiate their services to retain clients.
Client Retention
Keeping clients is crucial for RIAs. Client retention can be challenging due to various factors. For example, clients might leave if they are unhappy with their investment returns. Building strong relationships is key to retention.
RIAs need to communicate regularly and effectively. They need to show clients the value of their services. Providing consistent and reliable advice helps keep clients satisfied and loyal.
Operational Risks
Operational risks involve issues within the RIA’s own business. These can include technology failures, human errors, or security breaches. For example, a data breach can expose sensitive client information. RIAs must have strong systems in place to manage these risks.
This includes using secure technology and having good business practices. Training staff and having contingency plans can help reduce operational risks. Managing these risks is essential for maintaining trust and efficiency.
Future Trends In The RIA Industry

The RIA industry is constantly changing. Understanding future trends helps RIAs prepare and adapt. Key trends include technology integration, regulatory developments, changing client demographics, and the globalization of services. These trends will shape how RIAs provide their services and meet client needs.
Technology Integration
Technology is playing a bigger role in the RIA industry. New tools and software help RIAs work more efficiently. Technology can improve client services and make financial planning easier. Two important areas are AI and machine learning, and robo-advisors.
AI And Machine Learning
AI and machine learning are becoming more common in financial planning. These technologies analyze large amounts of data quickly. They can help RIAs make better investment decisions.
For example, AI can predict market trends and suggest the best investments. Machine learning helps in identifying patterns and risks. This technology can save time and improve accuracy. RIAs can use AI to offer more personalized advice to clients.
Robo-Advisors
Robo-advisors are automated platforms that provide financial advice. They use algorithms to create and manage investment portfolios. For example, a robo-advisor might recommend a mix of stocks and bonds based on a client’s risk tolerance.
These platforms are often cheaper than human advisors. They attract clients who want low-cost, efficient services. RIAs can use robo-advisors to complement their own services. This can help them reach more clients and offer a wider range of solutions.
Regulatory Developments
Regulatory developments will continue to impact the RIA industry. New laws and regulations can change how RIAs operate. For example, stricter reporting requirements may be introduced.
RIAs must stay updated on these changes to remain compliant. They need to adapt their practices and systems accordingly. Keeping up with regulatory developments ensures that RIAs can provide safe and legal advice to clients.
Changing Client Demographics
Client demographics are changing. More young people are seeking financial advice. Millennials and Generation Z have different needs and preferences compared to older clients. They prefer digital tools and quick access to information.
RIAs need to adjust their services to meet these new demands. Offering online consultations and using social media can help attract younger clients. Understanding these changes is important for growing and maintaining a client base.
Globalization Of Services
Globalization is another trend in the RIA industry. RIAs are reaching clients from different parts of the world. Technology makes it easier to offer services internationally. For example, video calls and online platforms allow RIAs to connect with clients anywhere.
This opens up new markets and opportunities. RIAs must understand international regulations and cultural differences. Globalization helps RIAs grow their business and offer diverse services to a wider audience.
FAQs
How Do RIAs Comply With Regulatory Requirements?
RIAs comply with regulatory requirements by following rules set by the SEC and state regulators. They register with the appropriate authority based on the amount of money they manage. RIAs keep accurate records and file reports. They follow ethical guidelines to act in their clients’ best interests.
How Do RIAs Stay Compliant With Changing Regulations?
RIAs stay compliant with changing regulations by keeping updated on new laws and rules. They attend training sessions and read industry news. Many RIAs hire compliance officers or consultants to help. They update their policies as needed. Regular audits and reviews ensure that they meet all requirements.
How Do RIAs Differ From Robo Advisors?
RIAs differ from robo-advisors in several ways. RIAs are human advisors who offer personalized advice. They understand each client’s unique needs and goals. Robo advisors are automated platforms that use algorithms to manage investments. They often cost less but do not provide personalized service.
What Technology Do RIAs Use To Manage Investments?
RIAs use various technologies to manage investments. They use portfolio management software to track and analyze investments. Financial planning tools help create client plans. Some RIAs use AI and machine learning to predict market trends. They also use communication tools to stay in touch with clients.
How Does An RIA Build A Diversified Portfolio?
An RIA builds a diversified portfolio by spreading investments across different asset classes. They include stocks, bonds, real estate, and other assets. This helps reduce risk because not all investments react the same way to market changes. RIAs consider the client’s goals when choosing investments.
What Kind Of Clients Do RIAs Typically Serve?
RIAs typically serve a wide range of clients. This includes individuals, families, and businesses. They help people save for retirement, college, and other financial goals. Some RIAs work with high-net-worth individuals who have complex financial needs. Others may focus on younger clients.
What Legal Structures Can An RIA Firm Have?
An RIA firm can have different legal structures. Common structures include sole proprietorships, partnerships, limited liability companies (LLCs), and corporations. Each structure has its own legal and tax implications. RIAs usually choose the best structure for their business needs.
Final Words
Registered Investment Advisors (RIAs) play a vital role in managing investments and financial planning. They provide expert advice, follow strict regulations, and offer personalized services. Understanding how RIAs work can help you make informed decisions about your financial future. Working with an RIA can provide peace of mind and help you achieve your financial goals.