What Is An Independent Financial Advisor? (Role & Benefits)
Effective financial planning is essential for securing a stable and prosperous future. It involves carefully managing your finances to achieve your long-term goals, and an independent financial advisor can play a crucial role in helping you in this process. But what is an independent financial advisor?
An independent financial advisor is a professional who provides unbiased financial advice without being affiliated with any financial institution. They recommend a variety of investment options and strategies from multiple sources. They ensure to meet the client’s best interests and financial goals.
In this guide, we will explore what an independent financial advisor is. We’ll discuss their roles, the benefits of working with one, and how they can significantly contribute to achieving your financial goals.
Key Takeaways
- Unbiased Advice: An independent financial advisor provides unbiased financial advice without ties to specific institutions.
- Diverse Options: Offers a wide range of investment options tailored to clients’ needs.
- Informed Decisions: Helps clients make informed decisions for achieving financial goals.
- Multiple Sources: An independent financial advisor can recommend products from multiple sources for the best client fit.
- Personalized Strategies: Ensures personalized financial strategies that align with individual goals.
What Is Financial Planning?
The financial planning definition involves creating a detailed strategy to manage your money to reach life goals. It covers budgeting, saving, investing, and planning for retirement. The process helps you understand how each financial decision you make affects other areas of your finances.
Why Consider An Independent Financial Advisor?

Considering an independent financial advisor is a wise choice for anyone seeking personalized and unbiased financial guidance. Unlike advisors tied to specific financial institutions, independent advisors have the freedom to choose from a wide range of products and services that best meet your individual financial needs. Here’s why you should consider an independent financial advisor:
- Personalized Service: An independent financial advisor tailors financial strategies to your unique goals and circumstances.
- Unbiased Recommendations: Offers product recommendations based solely on your best interests.
- Comprehensive Planning: Provides in-depth planning across all financial areas, including retirement, investments, and taxes.
- Flexible Options: Access to a broader array of investment opportunities not limited by affiliations.
- Trust and Transparency: Operates with a high level of transparency and is often a fiduciary, legally required to prioritize your interests.
Role And Responsibilities Of An Independent Financial Advisor
An independent financial advisor has many important roles that involve guiding clients to make informed financial decisions. Duties of financial advisors include helping clients with everything from daily budgeting to long-term investments. Here are the key responsibilities of an independent financial advisor:
Personalized Financial Planning
Independent financial advisors start by assessing your current financial status, including your income, debts, expenses, and personal financial goals. They use this information to create a detailed plan tailored to your needs. This plan might include strategies like setting monthly saving targets, advice on reducing expenses, or planning for large purchases.
For example, if your goal is to buy a home in the next five years, they will calculate how much money you need to save each month to achieve this goal.
Investment Management
These advisors provide expert advice on how to best invest your money to ensure it grows over time. They offer a range of investment options based on your risk tolerance and financial goals.
For example, if you’re a risk-averse individual, they may recommend stable investments such as bonds or mutual funds. They may suggest you allocate 70% of your portfolio to bonds, which are safer, and 30% to stocks, which are more volatile but offer higher returns.
Tax Planning
Tax planning involves strategies to minimize your tax liabilities within the framework of the law. An independent financial advisor can help you understand which investments and savings plans offer tax advantages.
For example, they may advise you to invest in a Roth IRA, where your money grows tax-free, or they might recommend using a health savings account to pay medical expenses pre-tax. This helps in saving you money on taxes each year.
Retirement Planning
Planning for retirement is crucial and involves calculating how much money you need to live comfortably after you stop working. Your advisor will help you understand various retirement savings options and how each contributes to your future stability.
They may suggest that you start with a basic 401(k) plan, contributing enough to get the full match from your employer, which is essentially free money towards your retirement.
Risk Management
Risk management is about identifying, analyzing, and taking steps to reduce financial risks to ensure your income and assets are protected.
This may involve diversifying your investment portfolio or purchasing life and disability insurance to safeguard against unexpected life events. For example, they might recommend having a mix of stocks, bonds, and real estate in your investment portfolio to spread out risk.
Estate Planning
Estate planning ensures that your assets are handled according to your wishes after your death. An advisor can help you draft a will, set up trusts, and make sure that your assets are transferred to your heirs with minimal tax implications.
For example, setting up a living trust can help your family avoid the long and public process of probate.
Ongoing Financial Advice
Life is unpredictable, and financial situations can change rapidly due to factors like a new job, inheritance, or changes in the economy. An independent financial advisor provides ongoing support, adjusting your financial strategies based on new developments in your life or in the financial markets.
When you get a new job with a higher salary, for instance, they can help you decide how to invest the extra income or whether to increase your retirement contributions.
Qualifications And Certifications Of An Independent Financial Advisor
Independent financial advisors must have proper education and certifications to guide their clients effectively. This ensures that they understand financial markets and can provide sound financial advice. Below, we detail the educational background and professional certifications necessary for independent financial advisors.
Educational Requirements
Independent financial advisors typically need a bachelor’s degree in finance, economics, business administration, or a similar field. This education helps them understand fundamental financial concepts, such as market dynamics, investment strategies, and economic indicators.
For example, a degree in finance may include courses on financial accounting, investment principles, and corporate finance. These are crucial for making informed financial decisions.
Professional Certifications

Professional certifications are essential for independent financial advisors. These certificates help the advisors show their commitment to ethical and professional standards. Here are some of the primary certifications:
Certified Financial Planner (CFP)
The Certified Financial Planner (CFP) credential is highly sought after in the financial planning industry. It requires candidates to pass a comprehensive exam that tests their ability to apply financial planning knowledge in real-life situations.
The certification process also includes education, a minimum of 6,000 hours of financial planning experience, and adherence to a strict code of ethics. For instance, a CFP may help a client develop a detailed plan for retirement savings, ensuring that they understand each step and its impact on their overall financial goals.
Chartered Financial Analyst (CFA)
Chartered Financial Analyst (CFA) is a prestigious certification for investment professionals across the globe. It involves passing three levels of exams that are widely considered challenging.
The curriculum includes topics such as ethical and professional standards, quantitative methods, economics, financial reporting and analysis, corporate finance, equity investments, fixed income, derivatives, alternative investments, and portfolio management.
A CFA charterholder typically possesses advanced investment analysis skills. These can be crucial in advising clients on how to optimize their investment portfolios.
Personal Financial Specialist (PFS)
The Personal Financial Specialist (PFS) credential is offered to CPAs who specialize further in personal financial planning. This certification requires CPAs to pass an exam and fulfill certain educational and professional experience requirements.
PFS holders have advanced knowledge in areas such as estate planning, retirement planning, and risk management. They can provide detailed strategies for managing wealth, minimizing taxes, and ensuring financial security for clients’ futures.
Chartered Financial Consultant (ChFC)
The Chartered Financial Consultant (ChFC) certification focuses on all aspects of financial planning, including insurance, income taxation, retirement planning, investments, and estate planning. The curriculum required for this certification is comprehensive. It ensures that professionals have a detailed understanding of the vast areas of financial planning.
ChFC professionals can offer sophisticated and detailed advice. They are especially useful in complex financial situations involving multiple goals and needs.
Securities Licenses
Securities licenses such as Series 6, 7, 63, 65, and 66 authorize financial advisors to sell various financial products and services. For example, the Series 6 license allows the sale of mutual funds and variable annuities, while the Series 7 license covers a broader range of securities.
Each license requires passing specific exams that test knowledge of market regulations, investment products, and ethical practices. Holding these licenses enables advisors to offer a wide range of investment options and tailor their financial strategies to the specific needs and objectives of their clients.
Benefits Of Hiring An Independent Financial Advisor
Hiring an independent financial advisor offers several advantages. They can help you manage your money better and reach your financial goals more effectively. They ensure that the advice they give is always in your best interest. Here’s a detailed look at the benefits:
Unbiased Advice
Independent financial advisors provide unbiased advice because they are not connected to any banks or investment companies. This means they suggest financial options that are the best for you, without any conflict of interest.
For example, they might recommend a savings account that offers a 4% interest rate from a small bank instead of a 2% rate from a large bank where they might get a commission.
Customized Financial Solutions
These advisors create financial plans that fit your specific needs. They look at your income, your goals, like buying a home or saving for college, and your comfort with risk to build a personalized plan.
This means every piece of advice they give is designed just for you, which can help you reach your financial goals more effectively.
Comprehensive Financial Planning
An independent financial advisor helps you with all parts of your financial life. They assist you in making plans for retirement, saving for education, buying insurance, and more.
By looking at the whole picture, they ensure that each part of your plan works well with the others. For instance, they may show you how saving more now could help you retire five years earlier.
Transparent Fee Structure
Independent financial advisors often have a clear fee structure, so you know exactly what you are paying for. They might charge a set fee per year or a percentage of the money they manage for you.
This makes it easy to understand the cost and helps avoid any surprises about fees later.
Fiduciary Responsibility
As fiduciaries, independent financial advisors are required by law to act in your best interests. This means they must choose the best financial options for you and cannot favor products that give them a higher commission.
Knowing this can give you confidence that your advisor is really looking out for you.
Long-Term Relationship
Working with an independent financial advisor often leads to a long-term relationship. They get to know you and your financial situation very well, which allows them to better anticipate your needs and adjust your financial plan as your life changes.
This ongoing relationship can provide you with continued support and advice, making it easier to navigate life’s financial challenges and opportunities.
How To Choose An Independent Financial Advisor

Finding the right independent financial advisor is crucial for achieving your financial goals. It’s important to choose someone who not only has the right qualifications and experience but also someone you can trust and communicate with easily. Here are some steps to selecting an advisor who can best meet your needs:
Assessing Qualifications And Credentials
Ensure the advisor has the necessary qualifications, such as a CFP (Certified Financial Planner) or a CFA (Chartered Financial Analyst). These certifications show that the advisor has undergone rigorous training and passed exams that cover a wide range of financial topics.
For instance, a CFP is required to complete thousands of hours of financial planning experience. This ensures they are well-equipped to handle complex financial situations. Checking for these credentials can help you trust their expertise.
Evaluating Experience And Expertise
It’s important to look at how long the advisor has been practicing and their areas of expertise. An advisor with a long track record in areas like estate planning or wealth management can be particularly beneficial if those services match your needs.
For example, an advisor who has over 20 years of experience and specializes in retirement planning might be more suitable for someone looking to prepare for retirement. It shows their ability to manage and grow retirement funds effectively over different economic cycles.
Understanding Fee Structures
Find out how the advisor charges for their services. Some advisors might charge a flat fee for their services. Others might charge a percentage of the assets they manage for you which is typically around 1-2%. Some might use a combination of both.
Understanding this upfront helps you evaluate whether you can afford the advisor and whether their fee structure aligns with your financial goals. For example, if you are just starting to build wealth, a flat fee advisor might be more cost-effective.
Checking References And Reviews
Always check references and read reviews from past clients. This will give you insight into the advisor’s performance and the satisfaction level of their clients. Positive feedback often includes praise for the advisor’s responsiveness, ability to tailor strategies to individual needs, and success in managing assets.
Negative reviews can alert you to potential red flags. For instance, finding multiple reviews mentioning poor communication or advice can be a sign to look elsewhere.
Conducting Interviews
Interview potential advisors to ask specific questions about how they would handle your finances and to gauge their understanding of your financial goals. During these interviews, ask about their approach to financial planning, how they’ve handled past financial crises, and how they think they can help you achieve your financial goals.
This step is crucial for assessing whether the advisor’s style and approach fit your expectations.
Compatibility And Communication Style
Finally, ensure that the advisor’s communication style and personality are compatible with yours. A good advisor should be someone you feel comfortable talking to about your finances, someone who listens to your concerns, and explains things in a way you understand.
For example, if you prefer detailed reports and regular updates, make sure the advisor is willing and able to provide that. Compatibility is essential for building a long-term relationship that will help you navigate your financial journey more effectively.
How Much Do Independent Financial Advisors Charge?
Choosing an independent financial advisor includes understanding how they charge for their services. Different advisors may use different fee structures, and the way they charge can affect how they manage your finances. Here are the details of different fee structures:
Fee-Only
Fee-only advisors charge a direct fee for their advice and do not receive any commissions from financial products. This could be a flat fee, like $2,000 for a full financial plan, or an annual fee, like $5,000, for managing all your financial needs throughout the year.
The fee structure of fee-only financial advisors is clear and straightforward. It ensures that the advice you receive is unbiased since the advisor doesn’t benefit from selling any products.
Commission-Based
Commission-based advisors make money by earning commissions from the financial products they sell. For example, if they recommend a mutual fund, they might get a 5% commission from the fund company if you invest.
This means if you invest $10,000, the advisor would earn $500. This fee structure may influence the advisor’s recommendations since they earn more if they sell more products.
Fee-Based
Fee-based advisors use a mix of fees and commissions. They may charge a basic fee for their advice, like 1% of your assets each year, plus they get commissions from any products they sell.
For instance, if they manage $100,000 of your money, they would charge $1,000 per year, and if they also sell you a product that pays a commission, they earn extra from that sale.
Hourly Rates
Some advisors charge an hourly fee for their services. This rate might range from $100 to $400 per hour, depending on their expertise and the complexity of the service provided.
Hourly rates are common for specific tasks, like an annual review of your investment portfolio or a consultation about your retirement plans.
Percentage of Assets Under Management (AUM)
Advisors who charge based on the percentage of the assets they manage for you usually set their fee between 0.5% and 2%. For example, if an advisor charges 1% and manages $100,000 of your assets, you would pay $1,000 each year.
This method aligns the advisor’s interests with yours; as your assets grow, so does their fee.
Retainer Fees
Retainer fees are regular payments made to the advisor for a comprehensive set of services. These fees are usually charged annually or quarterly and can range from $3,000 to $10,000.
The fee covers all ongoing advice, including financial planning, investment management, and regular updates. This structure is suitable for clients who need continuous, in-depth financial management.
Regulatory And Ethical Standards
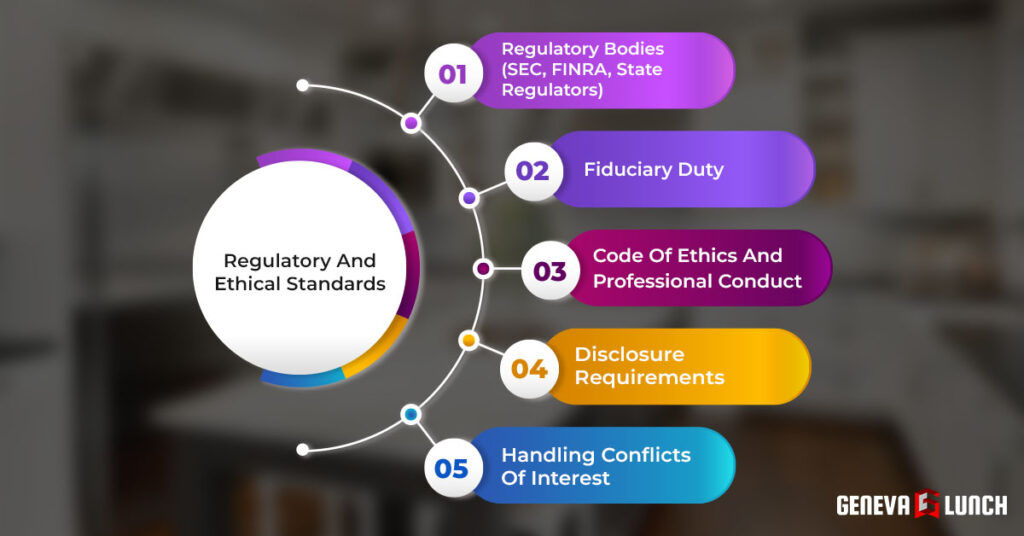
Independent financial advisors are required to follow strict regulatory and ethical standards. These help ensure they operate with integrity and in the best interest of their clients. These standards are designed to protect clients from unethical practices and to promote transparency and trust.
Regulatory Bodies (SEC, FINRA, State Regulators)
Independent financial advisors are regulated by various bodies depending on their practice size and type. The Securities and Exchange Commission (SEC) oversees advisors who manage assets totaling $110 million or more. It ensures they adhere to federal securities laws.
The Financial Industry Regulatory Authority (FINRA) regulates brokerage firms and their agents. It focuses on trading activities and brokerage. Advisors managing smaller amounts fall under state regulators who oversee their practices within specific states.
These regulators ensure advisors follow legal and ethical standards. It protects the investors from fraud and ensures transparency.
Fiduciary Duty
Fiduciary duty is a legal obligation that requires certain financial advisors to act solely in the best interest of their clients, putting the clients’ needs above their own. This means advisors need to make recommendations that best suit the clients’ financial goals and situations, without regard to the potential profits the advisor might earn from certain financial products.
For example, if an advisor is considering two similar investment products, they must recommend the one with the lower fees and better potential returns for the client, even if the other would earn the advisor a higher commission.
Code Of Ethics And Professional Conduct
The code of ethics and professional conduct for financial advisors includes principles such as integrity, honesty, and fairness. Advisors are expected to maintain confidentiality, provide accurate and thorough advice, and avoid deceptive practices.
They need to accurately represent their qualifications and the potential risks and returns of their recommended investments. For instance, advisors should not exaggerate the likely returns on an investment to make it more appealing or downplay the risks involved.
Disclosure Requirements
Advisors need to clearly disclose how they are compensated along with any potential conflicts of interest that might influence their recommendations. This transparency is crucial in helping clients make informed decisions.
For example, if an advisor receives a commission for selling a particular fund, they are required to inform the client of this fact. These disclosures help build trust and ensure clients are aware of any factors that might affect the advisor’s recommendations.
Handling Conflicts Of Interest
Handling conflicts of interest properly is essential for maintaining trust and credibility. Advisors must identify, disclose, and manage any conflicts of interest that could impair their ability to offer unbiased advice.
When an advisor stands to gain financially from recommending a particular product or service, they must disclose this to the client. They need to ensure that the recommendation is still in the client’s best interest. This approach helps prevent potential bias in the advice provided and ensures the advisor remains faithful to their fiduciary responsibilities.
FAQs
What Is The Difference Between A Financial Advisor And An Independent Financial Advisor?
The difference between a financial advisor and an independent financial advisor is their affiliation. A financial advisor works for a bank or firm and only suggests their products. An independent financial advisor doesn’t work for any institution and suggests a variety of products from different sources.
What Is The Role Of An Independent Financial Advisor?
The role of an independent financial advisor is to provide personalized advice on finances without being influenced by company ties. They help with budgeting, investing, planning for retirement, and other financial needs. Independent advisors focus solely on what is best for the client.
What Are The Disadvantages Of An Independent Financial Advisor?
One of the disadvantages of an independent financial advisor is that they often charge higher fees than advisors tied to financial institutions. Also, finding a qualified independent advisor can take time because you need to research and verify their reputation and credentials yourself.
Why Are Independent Financial Advisors Important?
Independent financial advisors are important because they provide unbiased financial advice. They are not pressured to sell specific products and can choose the best options for the client. This freedom allows them to tailor plans that truly fit the client’s financial goals and needs.
How Much Does Independent Financial Advice Cost?
The cost of independent financial advice varies depending on how the advisor charges. Some charge a flat fee, others charge a percentage of the assets they manage, often between 0.5% to 2%. There are also advisors who charge hourly rates. So, the financial advisor cost can vary.
Is An Independent Financial Advisor Better?
Whether an independent financial advisor is better depends on your needs. Independent advisors offer unbiased advice since they are not limited to any company’s products. However, if you prefer one-stop financial services from a single institution, a tied advisor might be more convenient.
Final Thoughts
In conclusion, an independent financial advisor is a crucial ally in managing your finances. By offering unbiased advice and a variety of investment options, they ensure that your financial plans align with your personal goals. Working with an independent advisor means receiving guidance that is tailored specifically to your needs, helping you navigate your financial journey with confidence.