Traditional IRA: Eligibility, Investment Types, Mistakes To Avoid

Planning for retirement is essential to ensure financial stability in your later years. One effective tool for building your retirement savings is a Traditional IRA, which offers numerous tax advantages. But what exactly is a Traditional IRA?
A Traditional IRA is a retirement savings account that offers tax benefits. Contributions may reduce your taxable income, lowering your tax bill. The funds grow tax-deferred, meaning you only pay taxes on withdrawals during retirement. This structure helps your savings grow more efficiently over time.
In this guide, we’ll discuss the key aspects of Traditional IRAs. It covers the eligibility, the investment types, the rules for contributions and withdrawals, and the mistakes to avoid.
Key Takeaways
- Tax-Deferred Growth: A Traditional IRA allows tax-deferred growth, enhancing your retirement savings.
- Tax Reduction: Contributions can reduce your taxable income, lowering your annual tax burden.
- Taxation at Withdrawal: Withdrawals during retirement are taxed as ordinary income.
- Contribution Age Limit: Eligible for contributions up to the age of 70½.
- Income-Based Deductions: Offers potential tax deductions based on your income level and filing status.
What Is A Traditional IRA?
A Traditional IRA, or Individual Retirement Account, is a type of savings account. It helps people save money for retirement in a tax-advantaged way. When you put money into a Traditional IRA, you might not have to pay taxes on that money until you take it out during retirement.
Importance Of Traditional IRAs In Retirement Planning
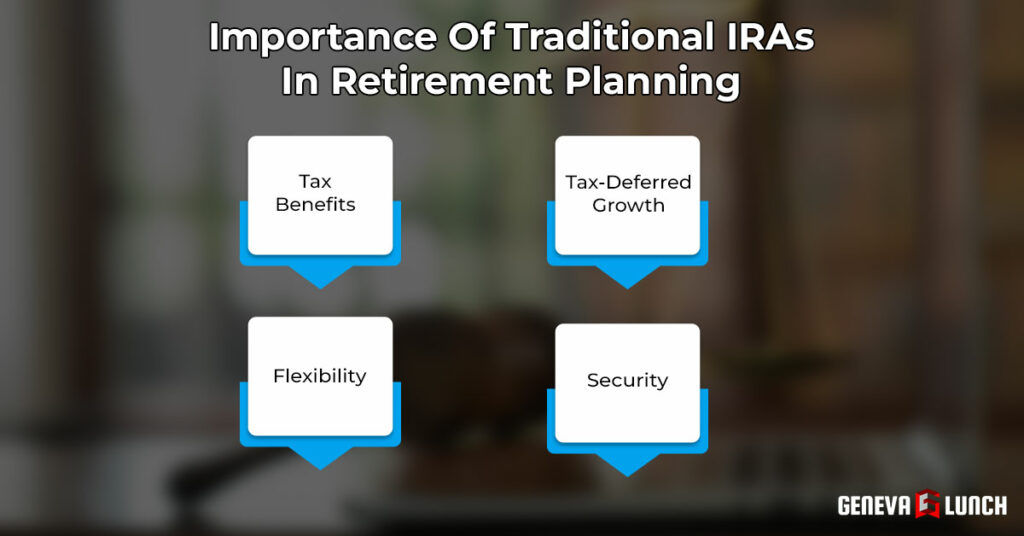
Traditional IRAs play a crucial role in retirement planning due to their tax advantages and flexibility in investment options. These accounts allow individuals to save for retirement in a tax-efficient manner. This can significantly impact long-term financial stability.
Here are some key Importance of Traditional IRAs:
- Tax Benefits: Contributions to a traditional IRA can be tax-deductible, reducing current taxable income.
- Tax-Deferred Growth: Investments grow without taxation until withdrawals begin, maximizing compound growth.
- Flexibility: Offers a range of investment options to suit different risk tolerances and financial goals.
- Security: Provides a dependable source of funds in retirement, ensuring financial independence and stability.
Eligibility For Traditional IRA
To open and contribute to a Traditional IRA, you must meet specific eligibility criteria. These are related to your age, income, employment, and marital status if your spouse is not working. These rules ensure that those contributing to an IRA are actively earning and meet the age and income guidelines set by the IRS.
Age Requirements
You can contribute to a Traditional IRA if you are under 70½ years old at the end of the year. This age limit allows individuals nearing retirement to continue adding to their retirement savings.
This can potentially enhance their financial security in later years. Once you turn 70½, you are no longer eligible to make new contributions.
Income Limits
To contribute to a Traditional IRA, your modified adjusted gross income (MAGI) must be under certain limits if you want to deduct your contributions on your tax return. For single filers in 2024, if your MAGI is between $78,000 and $88,000, the amount you can deduct decreases as your income increases.
For married couples filing jointly, the income phase-out range is between $129,000 and $139,000. Contributions can still be made with non-deductible funds if your income exceeds these limits.
Employment Status
Only individuals with earned income from employment or self-employment can contribute to a Traditional IRA. Earned income includes wages, salaries, commissions, and net income from self-employment. It does not include passive income such as rental property earnings, interest, or dividends.
This requirement ensures that contributions to the IRA come from active earnings. It supports the principle that IRAs are meant for workers saving towards retirement.
Non-Working Spouses
The IRS allows a working spouse to contribute to a Traditional IRA on behalf of a non-working spouse, provided the couple files a joint tax return. This rule enables families to double their retirement savings efforts even if only one spouse earns income.
For example, if a working spouse earns $50,000 annually, they can contribute up to $6,000 to their own IRA and another $6,000 to an IRA for their non-working spouse, as long as their combined contribution does not exceed their total earned income. This arrangement helps ensure both spouses can build their retirement savings.
Contribution Rules Of Traditional IRA

Contributing to a Traditional IRA involves understanding several rules. These include how much you can contribute each year, additional contributions for those aged 50 and above, the tax deductibility of your contributions etc.
Annual Contribution Limits
The maximum amount you can contribute to a Traditional IRA each year is $6,000 as of 2024. This limit applies to most people under the age of 50.
The contribution limit is set to ensure fairness in the tax advantages provided by IRAs and to encourage saving for retirement without excessive tax breaks.
Catch-Up Contributions For Age 50+
When you are 50 years or older, the IRS allows you to contribute an additional $1,000, increasing the total allowable contribution to $7,000. This provision helps older individuals who may need to boost their retirement savings as they near retirement age.
It acknowledges that older individuals might have less time to save and more urgency in preparing for retirement.
Deadlines For Contributions
Contributions to your Traditional IRA must be made by the tax filing deadline, which is typically April 15 of the following year.
For example, contributions for the 2024 tax year need to be made by April 15, 2025. This deadline helps taxpayers align their retirement savings contributions with their tax planning and filing.
Deductibility Of Contributions
The money you contribute to a Traditional IRA may be deductible on your tax return, which can reduce your taxable income and lower your overall tax burden.
However, the deductibility of your contributions depends on factors such as your income level, filing status, and whether you or your spouse have a retirement plan at work. For example, if your income exceeds certain limits, the amount you can deduct decreases.
Contribution Strategies
There are different strategies for contributing to an IRA that can help you optimize your savings. Some people might choose to contribute a lump sum at the beginning of the year to take advantage of compound interest throughout the year.
Others may prefer monthly contributions to spread out the financial impact. Choosing a contribution strategy that suits your financial situation and retirement goals is crucial for building a robust retirement fund.
Tax Benefits Of Traditional IRA

Saving in a Traditional IRA offers several tax benefits. These benefits make it an attractive option for many people planning for retirement. These include tax-deferred growth, tax-deductible contributions, and the potential to lower your current taxable income.
Tax-Deferred Growth
The money in your Traditional IRA grows without you having to pay taxes on the earnings each year. This means all the interest, dividends, and capital gains in the IRA accumulate tax-free until you withdraw them in retirement.
For example, if your IRA investment grows from $10,000 to $15,000 over several years, you do not pay taxes on the $5,000 growth until you take it out.
Tax-Deductible Contributions
The contributions you make to a Traditional IRA may reduce your taxable income for the year you make them. For example, if you earn $50,000 a year and contribute $6,000 to your IRA, you might only be taxed on $44,000 of income.
This deduction can lower your immediate tax bill, making saving for retirement more affordable.
Impact On Current Taxable Income
By making contributions to a Traditional IRA, you can reduce your taxable income. Lowering your taxable income may drop you into a lower tax bracket, reducing the percentage of tax you pay on your overall income.
For example, if contributing to your IRA brings your income from $50,000 down to $44,000, you might fall into a lower tax bracket. This can save you money on your taxes.
Future Tax Liabilities
While you save on taxes now, you will need to pay taxes on the money when you withdraw it during retirement. The amount you owe will depend on your tax bracket at the time of withdrawal.
It’s important to consider that your tax rate during retirement could be lower than during your working years, which can result in overall tax savings.
Investment Options Of Traditional IRA
A Traditional IRA offers a variety of investment options to suit different financial goals and risk tolerances. Knowing these options is important. They can help you strategically build a diversified retirement portfolio that aligns with your long-term financial plans.
What Is The Allowable Investment For A Traditional IRA?
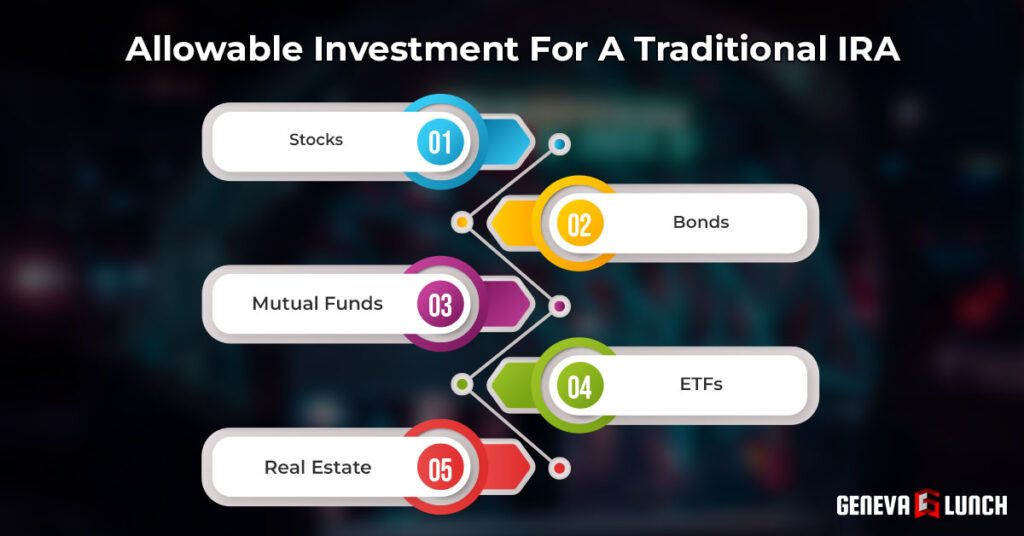
Traditional IRAs allow you to invest in various types of assets. These include stocks, bonds, mutual funds, ETFs, and real estate. These options provide flexibility and control over the risk and potential return of your retirement investments.
Stocks
Investing in stocks means buying shares of companies. When these companies do well, the value of your investment can increase significantly. For example, if you buy $1,000 worth of stocks and the market rises by 10%, your investment would grow to $1,100.
However, stocks can be volatile, meaning their value can also decrease quickly. They are best suited for those who have a longer time to invest before they retire, as this allows them to ride out market fluctuations.
Bonds
Bonds are essentially loans you give to corporations or governments in exchange for periodic interest payments plus the initial amount back after a certain period. They tend to be less risky than stocks but offer lower returns.
For example, investing $1,000 in a bond with a 3% interest rate will earn you $30 each year until the bond matures. Bonds are suitable for investors seeking steady income with lower risk.
Mutual Funds
Mutual funds collect money from many investors to purchase a broad portfolio of stocks, bonds, or other securities. This allows you to own a small portion of many investments, spreading out risk and reducing the impact of any single investment’s poor performance.
For example, if a mutual fund grows by 6% annually, a $5,000 investment would increase to approximately $8,954 in 10 years. Mutual funds are a popular choice for IRA holders due to their built-in diversification and professional management.
ETFs
Exchange-Traded Funds (ETFs) are similar to mutual funds but trade on stock exchanges much like individual stocks. They often have lower fees than mutual funds and provide the flexibility to buy or sell shares throughout the trading day.
An ETF that follows a major index, like the S&P 500, allows you to gain exposure to a broad market performance with a single purchase. This can be a cost-effective way to diversify your IRA investments.
Real Estate
Investments in real estate within a Traditional IRA typically occur through Real Estate Investment Trusts (REITs). REITs pool investor funds to buy properties, which they manage to generate rental income and potentially sell at a profit.
An investment of $10,000 in a REIT offering an annual return of 5% would grow to about $16,289 in 10 years. Real estate can provide a good source of passive income and act as a hedge against inflation.
Diversification Strategies
Diversification involves spreading your investments across various asset types to minimize risk. By not putting all your money in one type of investment, you can protect your portfolio from significant losses if one market sector performs poorly.
A well-diversified IRA may include a mix of stocks, bonds, ETFs, mutual funds, and real estate investments.
Risk Management
Effective risk management in your IRA means choosing investments that align with your risk tolerance and retirement timeline. It’s crucial to balance higher-risk investments like stocks and real estate with lower-risk options like bonds, especially as you approach retirement.
Periodic assessments and adjustments to your investment mix can help maintain the right balance. They can ensure that your retirement savings grow steadily while managing potential risks.
Withdrawal Rules And Penalties Of Traditional IRA
Traditional IRAs come with specific rules for when and how you can withdraw your money. Understanding these rules is essential. It helps you avoid financial penalties and to use your retirement savings effectively.
Age 59½ Rule
You are allowed to start withdrawing money from your Traditional IRA when you reach 59½ years old without facing any penalties. This rule is in place to encourage saving for retirement rather than early withdrawal.
When you withdraw funds before this age, a 10% penalty is typically applied to the amount you take out. This penalty is meant to discourage people from using these funds before retirement.
Do Traditional IRAs Have Required Minimum Distributions?
Traditional IRAs require you to begin taking withdrawals, known as Required Minimum Distributions (RMDs), starting April 1 following the year you turn 72. These withdrawals are mandatory. They are calculated based on your life expectancy and IRA account balance.
RMD Calculation
To figure out your RMD, you divide the total balance of your IRA at the end of the previous year by a life expectancy factor that the IRS provides.
For example, if your IRA balance is $100,000 and your life expectancy factor is 25.6 years, you must withdraw at least $3,906.25 that year.
Penalties For Missing RMDs
When you don’t take out the RMD, a steep penalty of 50% of the amount you failed to withdraw is charged. For example, if your RMD was $3,906.25 and you missed it, you would face a penalty of $1,953.13.
This penalty is enforced to ensure that the funds in IRAs are eventually used for retirement and not just accumulated indefinitely.
Early Withdrawal Penalties
Withdrawing money from your IRA before age 59½ usually results in a 10% penalty on the withdrawn amount. This penalty is in addition to the regular income tax you must pay on the distribution. This effectively reduces the amount you receive.
Exceptions To Early Withdrawal Penalties
There are exceptions that allow you to withdraw money early without penalties. These include expenses for buying your first home (up to $10,000), paying for education, and certain medical expenses that exceed 7.5% of your adjusted gross income.
These exceptions are designed to help you during significant life events without financial penalty.
Taxation On Withdrawals
Money taken from your Traditional IRA after reaching 59½ is taxed as ordinary income based on your current tax rate. For example, if you withdraw $10,000 and are in a 22% tax bracket, you would pay $2,200 in taxes on this withdrawal.
The idea is that you might be in a lower tax bracket in retirement than during your working years. This potentially lowers your tax obligation on these withdrawals.
Traditional IRA And Retirement Planning

A Traditional IRA is a powerful tool in retirement planning. It works alongside other savings to help you secure a financially stable future. Knowing how to use it in conjunction with other accounts and understanding its potential can enhance your retirement readiness.
Role In Overall Retirement Strategy
A Traditional IRA plays a critical role in retirement strategy by providing tax advantages that boost savings growth. Since contributions are often tax-deductible, and the investments grow tax-deferred, it helps in building a larger retirement fund.
For example, if you contribute $5,000 annually to your IRA and it grows at an average of 6% per year, after 30 years, your savings could exceed $395,000, assuming all contributions are deductible and taxes are deferred.
Integration With Other Retirement Accounts
Combining a Traditional IRA with other retirement accounts like 401(k)s or Roth IRAs can provide a more robust retirement plan. Each account has unique tax benefits and rules. For example, while a 401(k) might offer matching contributions from your employer, a Roth IRA offers tax-free growth and withdrawals.
Using these accounts together allows you to manage your tax liabilities better now and in retirement.
Strategies For Maximizing Benefits
To maximize the benefits of a Traditional IRA, consider timing your contributions and withdrawals strategically. Contributing early in the year maximizes the compounding growth. Planning your withdrawals to stay within a lower tax bracket can reduce the tax impact in retirement.
For example, if you’re close to moving into a higher tax bracket, withdrawing just enough to stay in the lower bracket can save you money.
Impact Of Inflation On Traditional IRA
Inflation can reduce the purchasing power of your savings in a Traditional IRA over time. When inflation averages 3% per year, the value of money decreases such that $100 today would only be worth about $74 in 20 years.
To combat this, it’s important to include investments within your IRA that have the potential to outpace inflation, like stocks or real estate investment trusts (REITs). This approach can help maintain the value of your retirement savings as prices rise over time.
Converting Traditional IRA To Roth IRA
Converting a Traditional IRA to a Roth IRA can be a strategic move depending on your current and expected future financial situation. Understanding the process, tax implications, benefits, drawbacks, and the best timing for conversion can help you make informed decisions.
Conversion Process
To convert your Traditional IRA to a Roth IRA, you must move the funds from your Traditional IRA into a Roth account. This can typically be done through a rollover or trustee-to-trustee transfer.
During this process, you instruct your IRA custodian to transfer the funds directly to the Roth IRA. This method helps avoid potential taxes and penalties associated with withdrawals.
Tax Implications Of Conversion
When you convert a Traditional IRA to a Roth IRA, the amount transferred is taxed as ordinary income in the year of the conversion. For example, if you convert $10,000 and are in the 22% tax bracket, you would owe $2,200 in taxes on the conversion.
This immediate tax cost is a key factor to consider because it requires upfront payment without the tax deferral benefit that a Traditional IRA offers.
Pros And Cons Of Conversion
There are some pros and cons of converting your Traditional IRA to a Roth IRA. Here are those:
Pros of Conversion:
- Traditional IRAs allow tax-deductible contributions, lowering your taxable income each year you contribute.
- The investments in a Traditional IRA grow tax-deferred, meaning you don’t pay taxes on the gains until you withdraw them at retirement.
- Starting at age 59½, you can make withdrawals without penalties, providing financial flexibility in retirement.
Cons of Conversion:
- Withdrawals from a Traditional IRA are taxed as ordinary income, which could be a higher rate depending on your total retirement income.
- Required Minimum Distributions (RMDs) begin at age 72, forcing you to withdraw funds whether you need them or not, potentially leading to higher tax liabilities.
- Early withdrawals before age 59½ typically incur a 10% penalty, discouraging access to funds in emergencies or for other needs before retirement.
Timing And Strategy For Conversion
The best time to convert is when your current tax rate is lower than you expect it to be in the future, or when your IRA’s value is lower, thus reducing the tax impact of the conversion. For example, converting during a year when you have unusually low income, or when the market is down, can minimize the taxes owed on the conversion.
Strategic planning with a financial advisor can help determine the optimal time to convert to align with your financial goals and tax situation.
Estate Planning With Traditional IRA

A Traditional IRA can be an important part of estate planning. It involves understanding how your retirement funds can be passed on to your heirs. Consulting a financial advisor for estate planning can be invaluable to make informed decisions.
Inheriting A Traditional IRA
When someone inherits a Traditional IRA, they take over the account and its assets. The rules for withdrawals depend on the relationship to the deceased and their age.
For example, a spouse inheriting an IRA might choose to treat it as their own, while other heirs may need to start taking distributions immediately based on their life expectancy.
Beneficiary Designations
It is crucial to designate beneficiaries for your Traditional IRA to ensure that your assets go to the intended heirs without going through probate. You can name anyone as a beneficiary, including spouses, children, friends, or even charities.
Keeping beneficiary designations updated, especially after major life events like marriage or the birth of a child, is essential to maintain the integrity of your estate plans.
Stretch IRA Rules
Previously, beneficiaries could extend distributions from an inherited IRA over their lifetime, often called a “Stretch IRA.” However, recent changes now require most non-spouse beneficiaries to withdraw all assets from an inherited IRA within 10 years of the original owner’s death.
This change can impact the tax and financial planning strategies for heirs.
Tax Implications For Heirs
The money withdrawn from an inherited Traditional IRA is taxable income for the heirs. This taxation can significantly impact the heir’s tax burden, especially if large withdrawals coincide with other income.
For example, if an heir inherits a $100,000 IRA and withdraws the entire amount in one year, it could push them into a higher tax bracket. This can increase their overall tax liability. Planning withdrawals strategically can help mitigate these tax impacts.
Common Traditional IRA Mistakes To Avoid
When managing a Traditional IRA, certain mistakes can hinder the growth of your retirement savings. They can also lead to unexpected financial consequences. Being aware of these common errors can help you make better decisions and maximize your IRA benefits.
Missing Contribution Deadlines
One common mistake is missing the annual contribution deadline, which is typically April 15th of the following year. For example, if you forget to make your 2024 contribution by April 15, 2025, you lose the chance to add up to $6,000 (or $7,000 if you’re 50 or older) to your IRA for that year.
This missed opportunity can significantly impact the compound growth of your retirement savings.
Overlooking RMDs
Failing to take Required Minimum Distributions (RMDs) starting at age 72 can lead to a heavy penalty. The IRS imposes a 50% penalty on the amount that should have been withdrawn but wasn’t.
For example, if your RMD was $4,000 and you missed it, you could owe $2,000 in penalties. It’s crucial to set reminders and possibly automate withdrawals to avoid this costly error.
Misunderstanding Tax Implications
Many IRA holders do not fully understand the tax implications of their contributions and withdrawals. For example, withdrawals are taxable as ordinary income, which could push you into a higher tax bracket, especially during years of large withdrawals.
Understanding how your IRA affects your taxes can help you plan better and possibly spread out withdrawals to manage tax burdens.
Poor Investment Choices
Choosing the wrong investments within your IRA can jeopardize your retirement savings. High-risk investments might offer high returns but can also lead to significant losses.
On the other hand, overly conservative investments may not keep pace with inflation. It’s important to balance your investment choices based on your age, risk tolerance, and retirement goals.
Regularly reviewing and adjusting your portfolio can help manage risks and optimize returns.
Neglecting Beneficiary Designations
Not keeping your IRA’s beneficiary designations up to date is a common oversight. Life changes such as marriage, divorce, or the death of a beneficiary can make your current designations outdated.
Ensuring that your IRA beneficiary designations reflect your current wishes is crucial for effective estate planning and can prevent legal complications for your heirs.
FAQs
How Do I Open A Traditional IRA?
To open a Traditional IRA, choose a financial institution like a bank, brokerage or mutual fund company. Then fill out an application form. Provide personal information like your Social Security number and employment details. Once set up, you can start making contributions to save for your retirement.
What Investments Are Allowed In A Traditional IRA?
In a Traditional IRA, you can invest in stocks, bonds, mutual funds, ETFs (Exchange-Traded Funds), and even real estate through REITs. These options allow flexibility in how you build your retirement savings. They help you to diversify your investments and potentially increase your returns over time.
How Do Traditional IRAs Impact My Taxes?
Contributions to Traditional IRAs can impact your taxes by reducing your taxable income in the year you make the contribution. The savings grow tax-deferred, meaning you don’t pay taxes on dividends or interest until you withdraw the funds. At withdrawal the money is taxed as ordinary income.
Can I Contribute To Both A Traditional IRA And A Roth IRA?
Yes, you can contribute to both a Traditional IRA and a Roth IRA in the same year. However, the total contribution to both Traditional and Roth IRA accounts cannot exceed the annual IRA contribution limit. This allows you to enjoy the benefits of both pre-tax and after-tax contributions.
What Happens If I Contribute Too Much To My Traditional IRA?
When you contribute more than the allowed limit to a Traditional IRA, you must pay a 6% tax each year on the excess contributions until you correct the mistake. To fix this, you can withdraw the excess contributions and any earnings on them before your tax return due date, including extensions.
Is It Worth Converting A Traditional IRA To A Roth IRA?
Converting a Traditional IRA to a Roth IRA can be worth it if you expect to be in a higher tax bracket in retirement than you are now. With a Roth IRA, you pay taxes on the money at the time of conversion, but then enjoy tax-free withdrawals later. Consider the tax implications before deciding.
How Do I Roll Over A 401(k) Into A Traditional IRA?
To roll over a 401(k) into a Traditional IRA, first open a Traditional IRA if you don’t already have one. Then request a direct rollover from your 401(k) plan provider, where they transfer your funds directly to the IRA. This avoids taxes and penalties that could come with receiving the funds yourself first.
How Do RMDs Affect My Retirement Income?
Required Minimum Distributions (RMDs) from a Traditional IRA must start at age 72, impacting your retirement income by potentially increasing your taxable income each year. This could affect your tax bracket and tax liability. Planning withdrawals strategically can help manage these impacts.
Final Thoughts
In conclusion, a Traditional IRA is a valuable tool for retirement planning, offering significant tax advantages that can help grow your savings effectively. By making pre-tax contributions, you can reduce your current taxable income and defer taxes until retirement. You can potentially lower your tax burden during your retirement years.
Understanding and utilizing a Traditional IRA is an important part of managing your finances and can greatly enhance your financial security in the future.